A forward test answers a question a backtest cannot: do the rules still behave when the prices have not happened yet? Each decision is made on a price that arrives after the test starts, so the rules cannot be fitted to it. QuantPower gives you three ways to run one. You can switch an algo on in Forward test instead of live. You can start a rule forward test that reads one instrument candle by candle. And you can trade by hand on your own Forward-test account, which behaves like a broker's book with its own test capital. All three use the same order rules as live trading and keep their records apart from your real money.
What Forward test does
| Part | What it does |
|---|---|
| Algos in Forward test | The same algo engine as live, with every entry, exit, stop and target, on your Forward-test account |
| Rule forward tests | A rule on one instrument, read on each new closed candle from 5-minute to daily |
| Forward-test account | One account per client, with ₹10,00,000 of test capital to start, for manual orders and algos |
| Orders | None sent to a broker or the exchange |
| Fills | At the price you see in the app, by the same order types as live: market, limit, SL and SL-M |
| Record | Every order, fill and position, an equity curve and running totals after charges |
| Limits | Up to 10 rule forward tests at a time; algos follow the normal algo limits |
| Price | 100 tokens per algo or rule forward test per 28 days; manual trades on the Forward-test account are free |
A short history of forward testing
Traders have always practised before they risked money. Before software, the practice was written down: a trader kept a notebook of the trades a system would have made each day, at the prices printed in the next morning's paper, and compared the notebook with the system's past record. The term "paper trading" comes from that habit.
As testing on past prices became routine, the limits of a backtest became clear. A rule that has been adjusted to fit one period will often look excellent on that period and fail on the next. In 1992 Robert Pardo set out a remedy in his book on trading system design: build the rules on one stretch of data, then test them on data that came after it and was not used to build them.1 Running a strategy forward on live prices is the strictest version of that idea, because the data does not yet exist when the rules are fixed.
Professional managers adopted the same step under other names. Many run a new strategy for months on a small account, or with no money at all, before it gets real capital, a stage often called incubation. Academic work on backtest overfitting gave the habit a firm footing: the more versions of a rule a researcher tries, the more likely the best one is a lucky fit, and only new data can tell the difference.2
In India, practice trading took a regulatory turn in 2024. On 24 May 2024 SEBI issued norms on sharing real-time price data with third parties, which stopped real-time prices from being used for virtual trading games and fantasy apps.3 A Forward test that runs on real-time prices therefore needs your own connected broker. Without one, it runs on the last close, exactly as the app shows it. Since 1 April 2026, retail algos in India also run through a broker under exchange rules, with each strategy registered.4 A Forward test is the place to see an algo behave before it goes through that path with real orders.
Three ways to run a forward test
Switch an algo on in Forward test
An algo in QuantPower is a set of legs with rules: when to enter, when to exit, what to do on a target or a stop-loss. When you switch it on, you choose where it runs: live, with orders at your broker, or in Forward test.
In Forward test the algo runs on the same engine as a live algo. It picks its strikes by the same rules, enters at the same times, checks the same stops, targets and trailing levels, re-enters by the same limits and exits at the same exit time. The only difference is where the orders go: to your Forward-test account instead of your broker. The algo card shows a "Forward test" tag, and the activity log records every step in plain words, just as it would live.
A Forward-test algo costs 100 tokens per 28 days. If you later switch the same algo on live in that period, you pay only the difference. If you paid for it as live, it can run in Forward test in the same period for nothing more.
Start a rule forward test
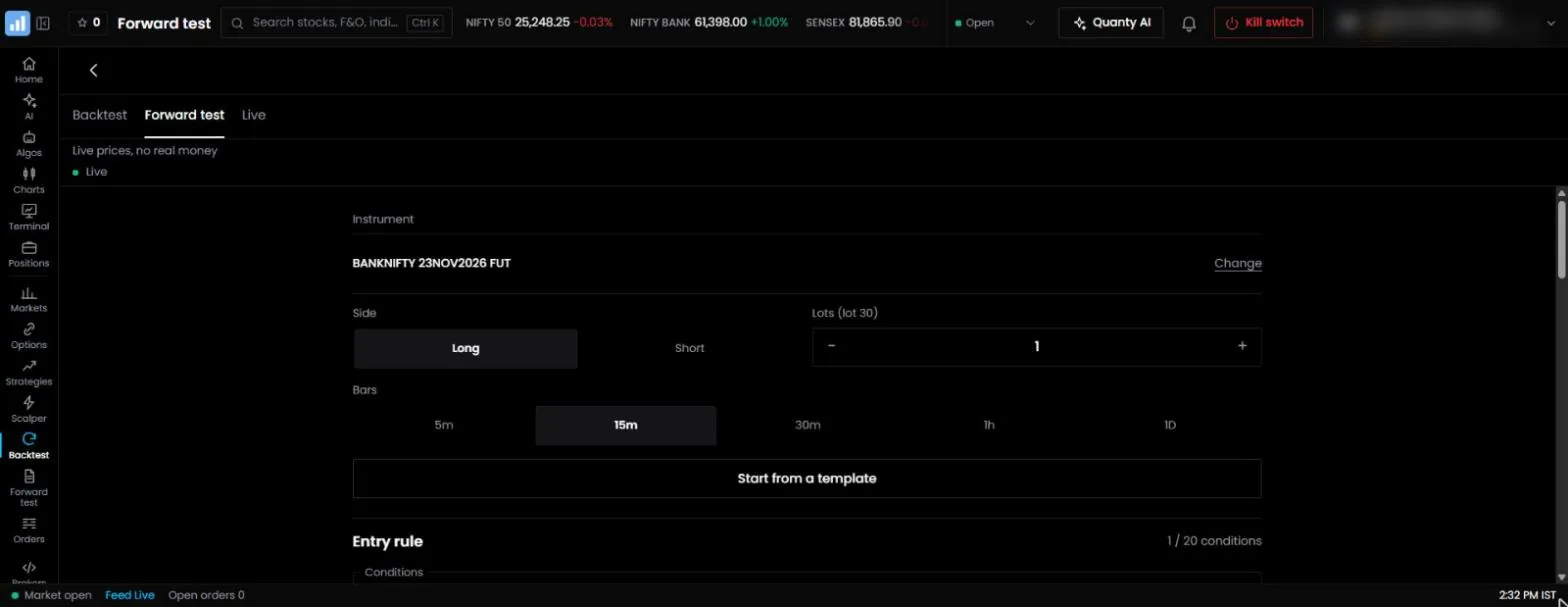
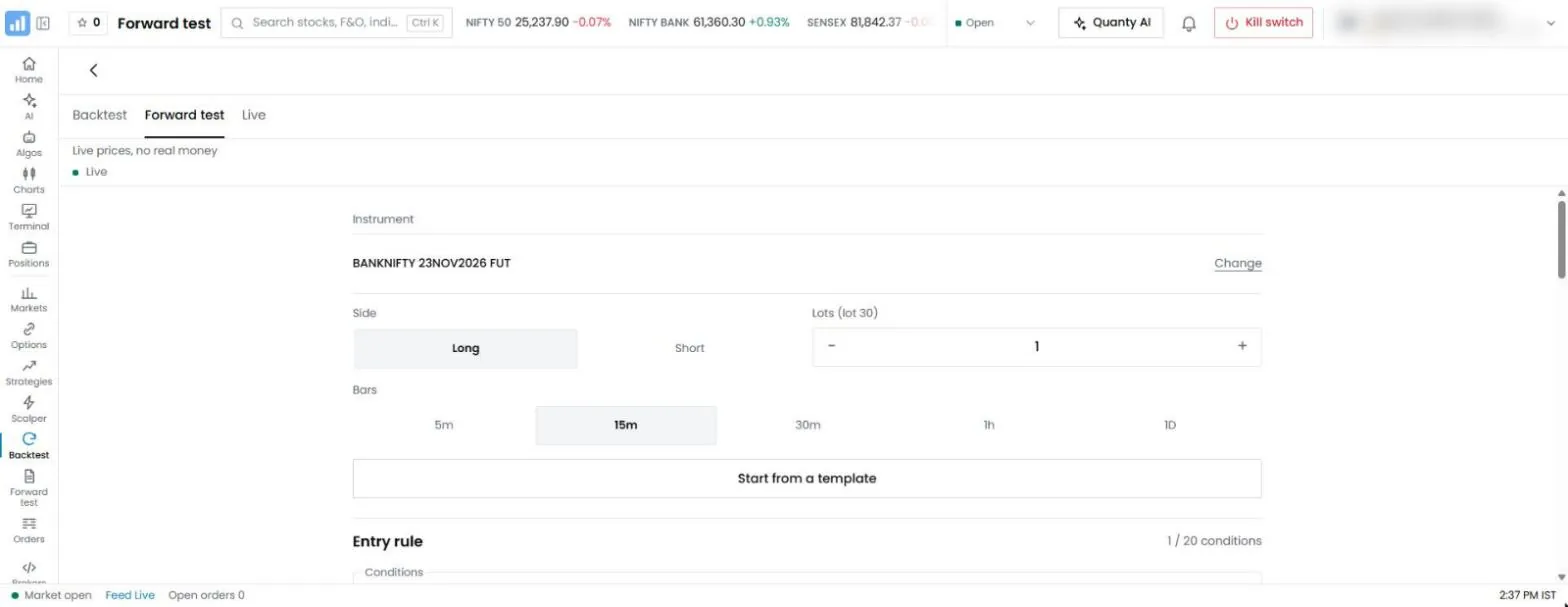
A rule forward test takes one instrument, a candle size and a rule, and reads the market one closed candle at a time:
- Set the rule. Pick the instrument, the candle size (5 minutes, 15 minutes, 30 minutes, 1 hour or 1 day), long or short, the quantity, the entry rule and, if you want them, an exit rule, a stop-loss and a target in per cent.
- Start it. The candles that exist at that moment are history. The test marks where it begins and takes no entry on any of them.
- Let candles close. The test waits for each new candle to close, reads it and applies the rule. While the market is closed, it does not run.
- Entries and exits follow fixed rules. An entry is taken at the close of the candle on which the entry rule turns true. An open trade exits on whichever comes first: the stop-loss or the target touched inside a later candle, or the exit rule true at a candle's close.
- Read the record. The screen shows the status, the open trade with its result so far, the closed trades, the equity curve and the totals.
- Stop it when you have seen enough, or let it run through more market conditions.
Up to 10 rule forward tests can run at the same time. Stop one to free a place. Each costs 100 tokens per 28 days.
Trade by hand on your Forward-test account
Every QuantPower client has one Forward-test account. It starts with ₹10,00,000 of test capital, and you can reset it to any amount from ₹1 lakh to ₹10 crore. Pick it in the order sheet the way you would pick a broker, and place orders exactly as you would live. Manual orders on the Forward-test account cost no tokens.
The account behaves like a broker's book:
- Margin. An order that needs more margin than the account has is refused, in plain words. An order that only reduces a position always goes.
- Intraday positions are squared off at the segment's square-off time, as a broker would do, by an order that says why.
- Overnight positions carry to the next trading day, and holidays are skipped.
- Expiry. A futures or options contract still held at expiry settles at the session close: options at their value against the underlying, futures at the underlying's price.
- Delivery buys move to holdings the next day.
- Reset clears the account and stops the algos running on it. Live algos are not touched.
How fills are decided
A forward test is only as honest as its fill rules, so these are fixed and written out.
On the Forward-test account, for algos and manual orders:
- Market orders fill at once at the price you see.
- A limit order at or better than the price fills at once at the price you see, as it would at an exchange.
- A resting limit order fills at its limit when the price crosses it.
- SL-M (stop-market) fills at the price once its trigger is reached.
- SL (stop-limit) becomes a resting limit once triggered, and fills only within its limit. A gap past the limit does not fill.
- Day orders left open are cancelled at the session close. IOC orders never rest. An after-market order goes live at the next session open.
For rule forward tests:
- Entry at the close. The entry price is the close of the candle on which the entry rule became true. The rule is checked only when a candle has closed, never in the middle of one.
- Stop-loss and target are percentages from the entry price. If a later candle's range touches a level, the trade exits at that level.
- Gaps. If a candle opens beyond a level, the trade exits at the open, not at the level, because that is where a real order would have found a price.
- Stop and target in one candle. When both fall inside the same candle, the data cannot show which came first, so the test takes the stop-loss.
- One position at a time. A new entry waits until the open trade has exited.
- Charges. An estimate is deducted from each round trip: 0.06% of turnover for intraday candles (5 minutes to 1 hour) and 0.13% for daily candles. It is shown separately, so you can see how much of the result charges took.
Real orders differ from all of this. They meet the bid-ask spread, partial fills, rejections and changes in margin that a forward test does not model. Expect live results to be a little worse than the forward test.
Prices and your broker connection
A forward test uses the price you see in the app. With your own broker connected, that price is live. Without a connected broker, SEBI's rules on real-time data mean the app shows the last close, so the Forward-test account and rule forward tests move on the last close and update when the next one arrives.3 An algo in Forward test reads the prices your account sees in the same way.
Your broker account is used for prices only. No order goes to it from a forward test. The Forward-test book is kept apart from your real money: your real portfolio, funds and risk rules read only your real brokers, and every Forward-test order and position is marked as such.
What you see on the screen
| Item | What it tells you |
|---|---|
| Status | Running or stopped, and when it started |
| Net P&L after charges | The result so far, with charges already taken off |
| Trades and win rate | How many trades closed and how many made money |
| Maximum drawdown | The largest fall from a peak in the equity curve |
| Charges | The total, and the basis used |
| Equity curve | How the result built up |
| Trade list | Entry, exit, price, the reason for the exit and the result of each trade |
| Algo card and activity log | For algos: today's legs and fills, the M2M, and a line for every entry, exit, re-entry and refusal |
| Forward-test positions on the chart | A line on the price scale marked "Forward test" |
Open the trade list and read a handful of trades from the start, the middle and the latest part. The reason shown for each exit makes it easy to check that the rules did what you meant.
From backtest to forward test to live
QuantPower treats testing as three steps, each answering a different question:
- Backtesting runs the rules over past data in seconds. It shows how they would have behaved across many market conditions, and throws out rules that never worked.
- Forward test runs the same rules on prices as they arrive. It shows whether the behaviour carries over when the market is unknown, and whether the entries and exits fire where you expect.
- Live runs the rules on your broker account with real orders, charges and slippage. Start with the smallest size, and raise it only when live results match the forward test.
A forward test cannot replace either neighbour. It is slow, because it needs real time to pass, and it produces fewer trades than a backtest. A backtest is fast but tests only the past. Used in order, each step removes a different kind of error before money is involved.
How long to run a forward test
There is no fixed period, but the length should match how often the strategy trades:
| Strategy type | Run the forward test for at least |
|---|---|
| Intraday option algos that trade every day | Four weeks |
| Expiry-day strategies | Eight expiries |
| Intraday rules on 5 to 15-minute candles | Four weeks |
| Hourly rules | Six to eight weeks |
| Daily rules | Two to three months, or at least 20 trades |
| Strategies that trade around events | At least two events of the kind they trade |
The goal is enough trades to see the strategy's normal days and at least one bad stretch. A forward test with five trades says very little either way.
A worked example: an expiry-day straddle in Forward test
Take an algo that sells the at-the-money Nifty call and put at 9:20 am on expiry day, with a stop-loss of 30% on each leg and an exit at 3:10 pm.
- Build the legs in the option strategy builder or load the Short Straddle template, and set the entry time, the stops and the exit time.
- Backtest it first, and keep it only if the trade list looks sensible.
- Switch it on in Forward test. The card shows the "Forward test" tag.
- On the first expiry day, watch the activity log at 9:20 am. Each leg should pick the at-the-money strike of that minute and fill at the price shown in the app.
- If a leg is stopped out, check that the stop triggered at 30% above its own entry price, and that the other leg stayed open as the rule says.
- At 3:10 pm, check that every open leg was squared off.
- After eight expiries, compare the Forward-test results with a backtest over the same days, with charges on both sides.
If the two agree, the algo is a candidate for live trading at the smallest size, at the cost of the difference between the Forward-test and the live price for the rest of the 28 days. If they do not agree, find out why first. The usual suspects are fills, the spread at entry time and stops that triggered inside a fast candle.
A worked example: a moving-average rule on a bank stock
Take a rule on a large bank stock on 1-hour candles: go short when the 20-period moving average crosses below the 50-period one, with a stop-loss of 1.5% and a target of 3%, and exit if the averages cross back.
- Backtest the rule over a period that includes both rising and falling months.
- Start a rule forward test with the same instrument, candle size, side and levels.
- For the first few days nothing may happen. The test takes no entry on the candles that already existed, and waits for the rule to turn true on a new close.
- When the first trade opens, check that the entry price equals the close of the candle that triggered it.
- When a trade exits, read the reason on the trade list: stop, target or exit rule.
- After six to eight weeks, compare the trade count, win rate and drawdown with the backtest's for the same weeks, with charges included on both sides.
How to read a forward test well
- Look at the number of trades first. A strong result on a handful of trades is noise.
- Compare with the backtest for the same weeks. The trades should be close. Large gaps point to a rule that depends on information not available at the moment of the decision, or to a difference in prices.
- Check the drawdown. Ask whether you could have sat through the largest fall with real money in the strategy.
- Read the exit reasons. If most losses come from the stop and most wins from the exit time, that tells you where the strategy gets its result.
- Take charges seriously. A strategy whose gross profit is only slightly above its charges has little room for slippage.
- Do not change rules during the test. A change starts a new test. Note the idea and run it separately.
- Run versions side by side, but only a few. Up to 10 rule forward tests can run together, so you can compare two or three versions on identical candles. Testing many versions and keeping the best is a form of overfitting.
Common mistakes
- Judging after a good week. A short run says little. Wait for the period that fits the strategy.
- Stopping the test on a bad day. The bad days are what you are testing for.
- Treating the result as a forecast. It is a record of how the rules behaved on the prices that arrived during the test.
- Skipping the backtest. A forward test is slow, so use the backtest to throw out rules that never worked.
- Testing without your own broker's prices. On the last close, an intraday strategy cannot be judged properly. Connect your broker for live prices.
- Using a test size you would never trade. Set the Forward-test capital and quantities to what you would use live, or the drawdown will mean nothing.
- Going live at full size. Even a clean forward test is not live trading. Start with the smallest size.
Forward test and the rest of QuantPower
Forward test works with the other parts of QuantPower rather than replacing them. The rules you build in the strategy builder feed both the backtest and the forward test. Signal algos can use your Forward-test account in place of a broker, so an indicator signal can place its orders there. The strategy performance screens keep the record of an algo once it runs live.
The account-level safety controls, the kill switch, the daily loss limit and Smart Exit, cover your real brokers, where real orders are placed. The Forward-test book is separate and never mixes with real money, so a reset of the Forward-test account never touches a live algo, and a live square-off never touches a Forward-test position.
Forward test with Quanty and your own AI app
Quanty, the AI assistant in the QuantPower app, can take you from an idea to a Forward test without filling every field by hand. Describe the strategy in words, for example "sell the at-the-money Nifty straddle at 9:20 on expiry day with a 30% stop on each leg". Quanty builds it for you to check, backtests it and runs a risk check that flags a missing stop-loss or a sold option without a hedge. It saves the algo switched off.
Quanty can then prepare a start in Forward test. That makes a confirm card in the app, and only your tap starts it. Quanty cannot switch an algo on by itself, in Forward test or live, and no AI tool in QuantPower can.
If you use your own AI app, such as Claude or ChatGPT, Connect AI links it to your QuantPower account with the permissions you choose. It can read your algos and their day, backtest your rules and save an algo switched off. Starting it, in Forward test or live, stays with you in the app.
Quanty and a connected AI app are software, not advisers. They will not tell you which strategy to run. They help you write down your own rules, test them and read the result.
Forward test for signals
A signal algo watches a condition, such as a price level, an indicator crossing another or a rule of up to 20 conditions on the chart's indicators and patterns, and acts when it fires. In one-touch mode it prepares an order for your touch. In auto mode it places the order itself, with every risk check.
Auto mode needs somewhere to send the order: a connected broker, or your Forward-test account if you pick it. Picking the Forward-test account is the safe way to watch a signal fire on live prices for a few weeks, see where its orders would have filled and how often it would have traded, before you point it at real money. Any change to the condition or the order disarms an auto signal, so a signal you edit during the test has to be armed again, and its record starts afresh.
Where forward testing is going
Two trends make forward testing more important. The first is speed: strategies can now be written and backtested in minutes, including by AI assistants such as Quanty, so more untested ideas reach the point of going live. A forward test is the brake that keeps an idea from going straight from a sentence to real money. The second is regulation: with every retail algo in India running through a broker under exchange rules since 1 April 2026, traders are expected to know how their algo behaves before it trades. A record of how it ran on live prices, with every entry, exit and refusal logged, is the plainest way to show that.
Pricing
Forward test is priced in tokens (1 token = ₹1, GST extra). An algo or a rule forward test costs 100 tokens per 28 days, charged for the days left if you start part-way through a cycle. Manual orders on your Forward-test account are free. An algo paid for as live runs in Forward test in the same period for nothing more, and one paid for as Forward test that goes live pays only the difference. A backtest costs 2 tokens, with the first 10 each week free. See pricing for the full list.
Related guides
- Paper trading platform for options: how to practise options trading and judge a practice result
- Algo trading for retail traders: running your rules as algos on your broker account
- Strategy builder: entry, exit and stop rules on the same legs
Start with 500 free tokens
Connect your broker, build a strategy and test it on paper before a single live order goes out.
Frequently asked questions
Does a forward test place orders with my broker?
No. Every Forward-test order goes to your Forward-test account, which is kept apart from your real brokers. Nothing reaches your broker or the exchange, and no real money is at risk.
How much test capital does the Forward-test account have?
It starts with ₹10,00,000. You can reset it to any amount from ₹1 lakh to ₹10 crore. A reset clears the account and stops the algos running on it.
Can I switch the same algo from Forward test to live?
Yes. Switch it off and switch it on live. If you paid for it as Forward test in the current 28 days, going live costs only the difference. A restart always stays where the algo ran, so an algo never moves from the Forward-test account to real money on its own.
How many rule forward tests can run at once?
Up to 10 at the same time. Stop one to free a place. Algos in Forward test follow the normal algo limits, up to 20 running at a time.
Does a forward test keep running when I close the app?
Yes. Algos and rule forward tests keep running when the app is closed, so you can close the app and read the result later.
Why do live results differ from a forward test?
Live orders meet the bid-ask spread, partial fills, rejections, margin changes and full charges, and decisions feel different with real money at stake. Expect live results to be a little worse.
References
- Robert Pardo, *Design, Testing and Optimization of Trading Systems* (1992), on testing rules on data not used to build them
- David H. Bailey, Jonathan M. Borwein, Marcos López de Prado and Qiji Jim Zhu, "The Probability of Backtest Overfitting", *Journal of Computational Finance* (2016)
- SEBI, circular "Norms for sharing of real time price data to third parties", 24 May 2024 (sebi.gov.in)
- SEBI, circular on safer participation of retail investors in algorithmic trading, 4 February 2025, in force for every broker from 1 April 2026 (sebi.gov.in)
- QuantPower: Forward-test account, fill rules, limits and prices, from the app's code and price list, checked 12 November 2026