This guide explains each column of the chain, how to read it row by row, and how traders use open interest, the put-call ratio, implied volatility, max pain and the expected move. It walks through two worked readings, an expiry-day morning and the choice of strikes for an iron condor, and ends with the mistakes that cost option traders most. Nothing on the chain is a signal by itself. It is a map of where traders are positioned and what the market is charging for options, and the decision that follows is yours.
What the Nifty option chain shows
| Part | What it shows |
|---|---|
| Strikes | Every listed strike for the chosen expiry, calls on the left and puts on the right |
| Prices | Last traded price, change, and the best bid and ask with their quantities |
| Activity | Volume traded today and open interest, with today's change in open interest |
| Volatility | Implied volatility for each strike |
| Greeks | Delta, gamma, theta and vega for each strike |
| Summary | Put-call ratio, max pain, the strikes with the largest open interest, and the ATM straddle |
| Expiries | The current weekly expiry, the following weeklies and the monthly contracts |
A short history of the Nifty option chain
Nifty options began trading on the NSE on 4 June 2001, as monthly European-style contracts settled in cash.1 For their first decade they were a professional's instrument, and the "option chain" was a page of numbers on the exchange's website that few retail traders read.
Three changes brought the chain to the centre of Indian trading. The first was weekly options: Bank Nifty weekly contracts arrived in 2016 and Nifty weekly contracts in February 2019, and expiry day became a weekly event.1 The second was cheap online broking, which put a live chain, with open interest and Greeks, in every trading app. The third was the growth of option selling by individual traders, for whom the chain is the main screen: where the open interest is, how wide the spreads are and how much premium each strike pays.
The rules have kept changing the chain's shape. SEBI's measures of 1 October 2024 limited weekly expiries to one benchmark index per exchange, which left Nifty as the NSE's only weekly index option, and raised the minimum contract size.2 From 1 September 2025 the NSE moved Nifty's weekly and monthly expiries to Tuesday.3 From the January 2026 series the Nifty lot became 65 units.4 A chain read in 2023 and one read today describe different markets, and the habits traders built on old expiry days and lot sizes need checking against the current contract.
How the chain is laid out
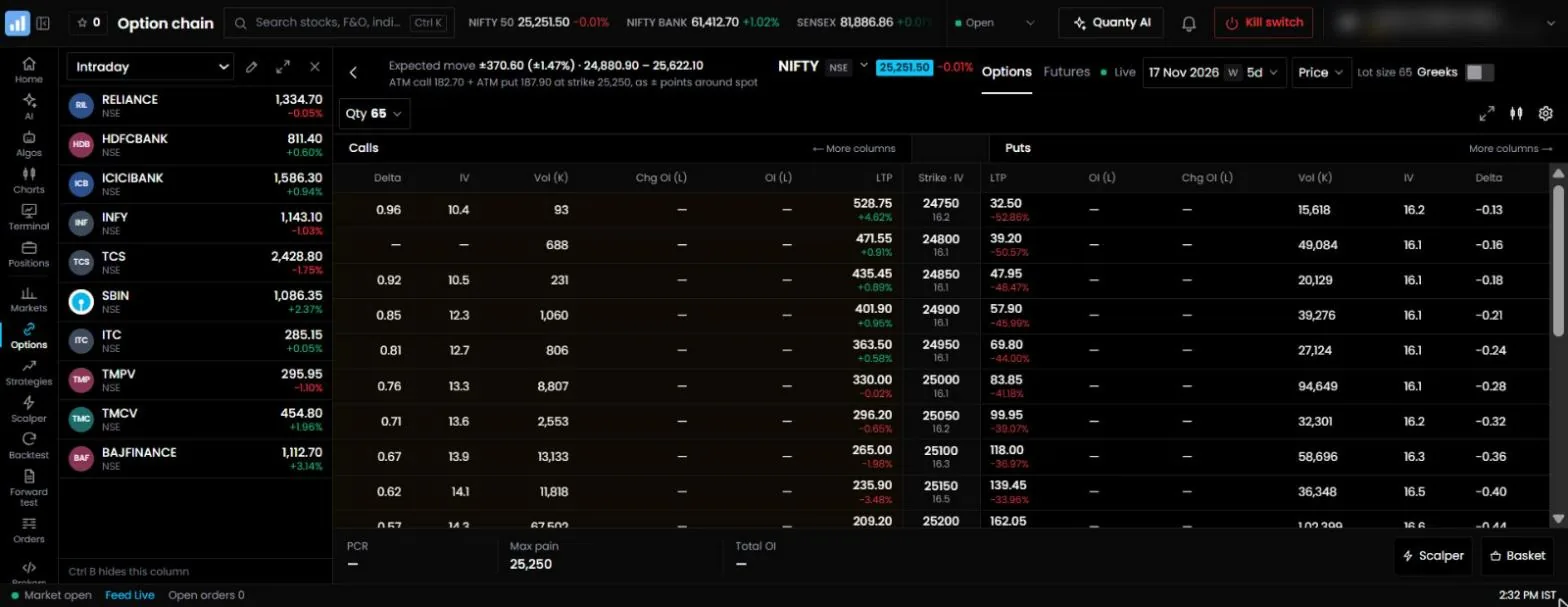
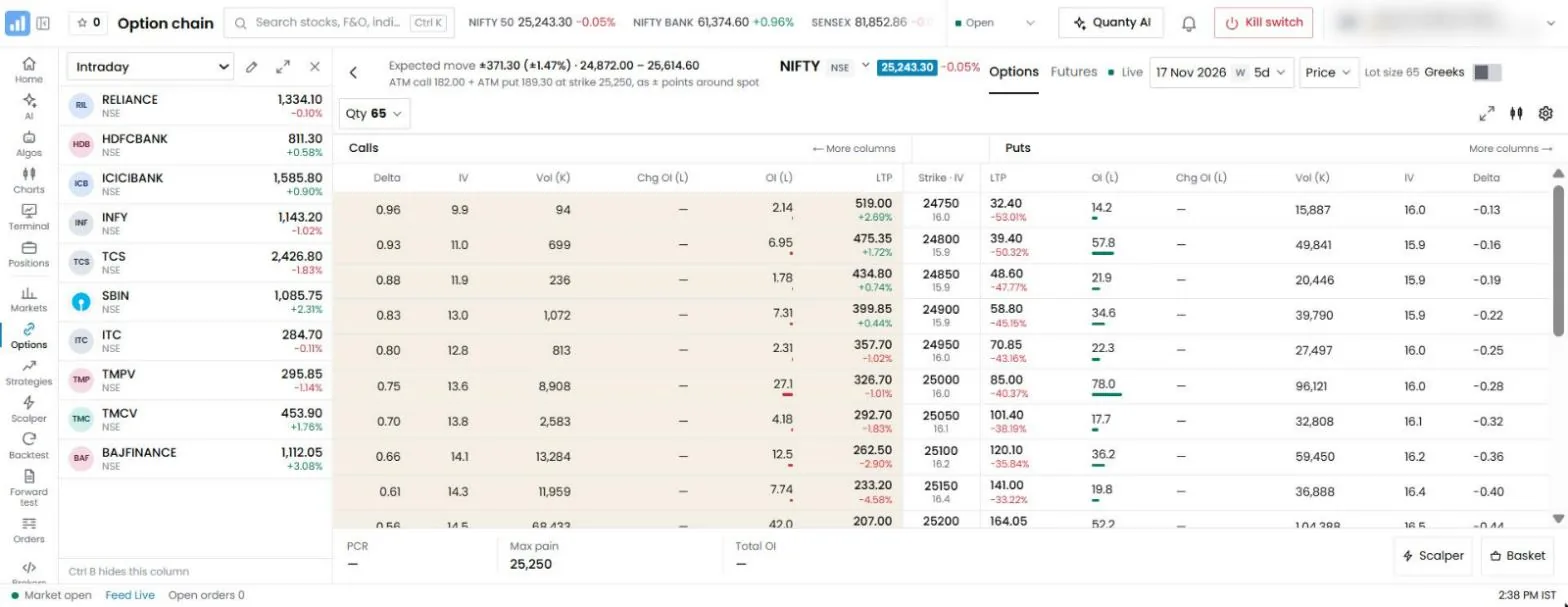
The chain is split into two halves around a central strike column:
- Calls on the left, puts on the right.
- Strikes in the middle, from low to high.
- The at-the-money strike is the one nearest to the current Nifty level, usually highlighted.
- In-the-money options are often shaded: calls below the market and puts above it.
You choose the expiry at the top: the current weekly expiry, the next weekly expiries or the monthly contracts. Nifty strikes are listed every 50 points, with the exchange adding strikes as the market moves so that there are always strikes well above and below the current level. The monthly contracts carry strikes further out than the weeklies, because they have longer to run.
What each column shows
| Column | Meaning |
|---|---|
| LTP | The last traded price of the option |
| Change | The change in price from the previous close |
| Bid and ask | The best prices to sell and to buy now, with quantities |
| Volume | Contracts traded today |
| OI | Open interest: contracts open at present |
| Change in OI | How much open interest has changed today |
| IV | The implied volatility of that option |
| Delta, theta, vega, gamma | The option's Greeks |
The bid-ask spread is especially important: it is the cost of trading the option. Near-the-money Nifty strikes usually have tight spreads of a few paise to a rupee; far strikes are wider, and on a quiet afternoon a far strike can show a spread that is a large share of its price.
Reading one row
Here is one row of a model chain, with Nifty at 25,000 and four days to expiry. The figures are illustrations.
| 25,000 call | Strike | 25,000 put | |
|---|---|---|---|
| LTP | ₹212 | 25,000 | ₹198 |
| Bid / ask | ₹211.5 / ₹212.5 | ₹197.5 / ₹198.5 | |
| IV | 13.8% | 14.6% | |
| Delta | 0.52 | −0.48 | |
| Theta (a day) | −₹16 | −₹15 | |
| Change in OI | Up, steady through the morning | Up, faster after a dip |
Read across: the call and the put at the money are priced close together, which is normal; the put's IV is a little higher, which is the usual skew; each loses about ₹15 to ₹16 of value a day from time decay, which an option seller collects and a buyer pays; and new positions are building on both sides. The ATM straddle, the call plus the put, is ₹410, which is the market's price for a move in either direction before expiry.
Reading open interest on the chain

Open interest shows where positions are concentrated. Traders commonly read:
- The call strike with the highest OI above the market as possible resistance, because many calls have been written there.
- The put strike with the highest OI below the market as possible support.
- Large changes in OI during the day as signs of new positions being built.
The reading assumes most open interest at far strikes belongs to sellers, which is often true for index options but never certain. OI does not show who started a position, and levels shift as traders roll positions from one strike to another. Watch the change in OI more closely than the total: a strike where calls are being added as the market rises towards it tells you more than a strike that has carried large OI all week.
Change in OI combined with the option's price gives four readings, the same as for futures:
| Option price | Open interest | Usual reading |
|---|---|---|
| Up | Up | New buying of the option |
| Down | Up | New writing of the option |
| Up | Down | Writers covering, buying back |
| Down | Down | Holders selling out |
Our Nifty PCR guide explains how to read OI alongside price across the whole chain.
PCR from the chain
The put-call ratio divides total put open interest by total call open interest for the expiry.
With 1.10 crore units of put OI and 1.00 crore of call OI, PCR is 1.10. A PCR above 1 means more open interest in puts than calls. Traders read it both as a sign of put writers supporting the market and, at extremes, as a contrarian signal of crowded positioning. Compare PCR with its own recent range rather than with a fixed value, and compare it for the same expiry from day to day: PCR on the first day of a new weekly series and on its last morning measure very different things.
Max pain
Some option chains show max pain: the strike at which option buyers as a group would lose the most at expiry, or, put the other way, at which the total value of all open options would be smallest. It is worked out by taking each strike as a possible expiry price and adding up what every open call and put would be worth there.
Some traders expect Nifty to finish near max pain, on the idea that option writers, who hold the larger positions, defend it. The evidence is mixed, and the level moves during the week as open interest changes. Treat it as context about where positions are concentrated, not as a target.
Reading IV on the chain
- IV by strike: out-of-the-money puts usually show higher IV than calls the same distance away. This skew reflects demand for protection against a fall.
- IV across expiries: an expiry just after a scheduled event, such as a policy decision or a Budget, often shows higher IV than the one before it.
- IV over time: compare today's ATM IV with its own history using the implied volatility calculator, and with India VIX for the broad level.
High IV makes options expensive, which favours sellers if the market then moves less than priced, and hurts buyers who need a large move to overcome the premium. Low IV does the reverse. Neither is a forecast: high IV often comes with good reason. A sudden rise in IV across the whole chain, with no change in the index, usually means the market expects news; a fall after an event, the "IV crush", can take value out of options even when the index moves the way a buyer hoped.
The expected move
The ATM straddle price turns into a range: the spot plus and minus the straddle. With Nifty at 25,000 and the weekly ATM straddle at ₹410, the expected move to expiry is about ±410 points, or ±1.6%, from about 24,590 to 25,410. Nifty often finishes inside this range, and the weeks it does not are the ones that hurt option sellers most. Use the range to see whether a strategy's short strikes sit inside or outside what the market is pricing, not as a promise that the index will stay within it.
The Greeks on the chain

Each strike's Greeks tell you how its price will respond:
- Delta is how much the option moves for a one-point move in Nifty. Traders also read it roughly as the chance the option finishes in the money: a 0.20 delta call has, on the model's assumptions, about a one-in-five chance.
- Gamma is how fast delta changes. It is highest at the money and rises sharply in the last days before expiry, which is why at-the-money options swing so fast on expiry day.
- Theta is the value an option loses in a day with nothing else changing. It speeds up as expiry nears.
- Vega is how much the option moves for a one-point change in IV. Longer expiries have more vega.
See the options Greeks for each one in depth.
Using the chain to choose strikes
- Buyers often look at ATM or slightly in-the-money strikes with tight spreads and enough volume, so that a move in Nifty shows up in the option's price and the exit is not costly.
- Sellers often choose strikes by delta, such as 0.15 to 0.30, or beyond the high-OI strikes, and check that the premium is worth the risk after charges.
- Spreads pair strikes from the same expiry, so check both legs' liquidity. A spread whose bought leg has a wide spread costs more to enter and exit than its payoff suggests.
Model the chosen position in the option profit calculator before trading.
From premium to rupees
The chain shows premiums per unit. What you pay or receive is the premium times the lot size times the number of lots. With a lot of 65, the ₹212 call in the row above costs ₹13,780 for one lot; the ₹410 straddle brings in ₹26,650 a lot for a seller. A 10-point move in a premium is ₹650 a lot. Keep the conversion in mind when a cheap-looking strike tempts you: a ₹5 option is ₹325 a lot, and ten lots of it can disappear in an afternoon.
What buyers and sellers look for
An option buyer pays time value and needs a move, so on the chain he looks for:
- strikes with tight spreads and steady volume, usually near the money;
- IV that is not unusually high for the expiry, so he is not overpaying for the move;
- enough time to expiry for the move he expects, with theta in mind;
- open interest that is not stacked against his direction just beyond his target.
An option seller collects time value and needs the market to stay within a range, so he looks for:
- strikes outside the expected move, often by delta;
- premiums large enough to be worth the risk after charges;
- heavy open interest beyond his short strikes rather than in front of them;
- a wing he can buy cheaply enough to cap the loss.
Both look at the same columns. They read them for opposite things.
A worked example: an expiry-day morning
It is Tuesday, expiry day, and Nifty opens at 25,060. A trader planning a short-dated trade reads the chain at 9:30 am.
- ATM and the straddle. The 25,050 strike is at the money. The straddle is ₹95, so the market prices a move of about ±95 points to the close.
- Open interest. The largest call OI sits at 25,200 and has grown since the open; the largest put OI sits at 24,900 and is flat.
- IV. ATM IV is higher than yesterday's close, which is common on expiry morning and means time value will fall fast if the market stays still.
- Spreads. Strikes within 200 points have spreads under ₹0.50; beyond 300 points, spreads widen.
- The plan. Whatever trade follows, the trader writes down the level that proves it wrong, such as a 15-minute close above 25,200 where calls are being written, and sizes the position so that a move to that level costs no more than his budget.
The chain did not say what to trade. It said what the market is pricing, where positions are, and what it costs to trade each strike. On a different morning, with the straddle at ₹140 and put OI growing fast below the market, the same steps would lead to a different plan, or to no trade at all.
A worked example: choosing strikes for an iron condor
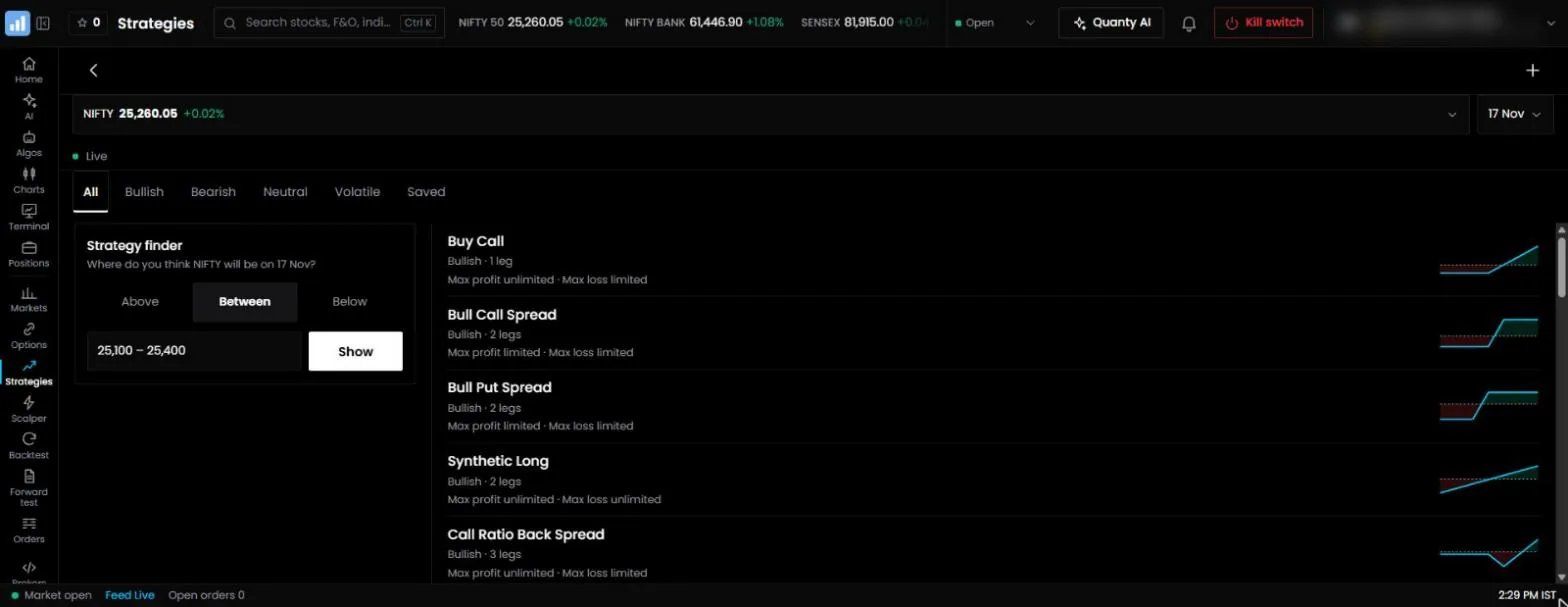
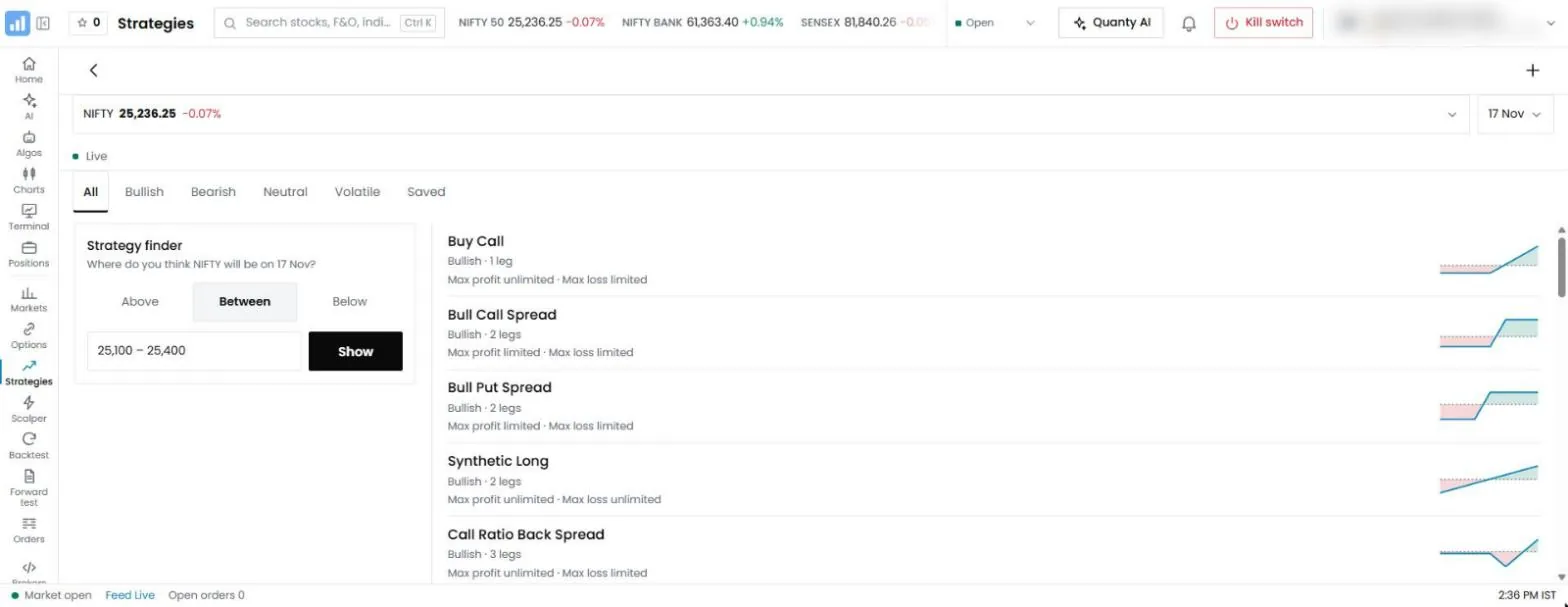
With Nifty at 25,000 and a week to expiry, a trader wants to sell a range-bound structure with defined risk.
- Expected move. The ATM straddle is ₹410, so the expected range is about 24,590 to 25,410.
- Short strikes by delta. The 25,450 call and the 24,550 put have deltas near 0.20, just outside the expected range.
- Open interest check. Call OI is heavy at 25,500 and put OI at 24,500, so the short strikes sit just inside the strikes with the most open positions.
- Wings. Buying the 25,650 call and the 24,350 put caps the loss at 200 points less the credit received.
- Liquidity. All four strikes show spreads under ₹1, so entering and exiting will not cost much more than the model suggests.
The trader then models the four legs in the option profit calculator, checks the maximum loss against his budget and the margin for the hedged position, and decides. The figures are illustrations.
Reading the chain through the day
The chain tells a different story at different hours.
The first half hour. Spreads are often wider, IV can jump at the open, and open interest from the previous day has not yet been updated with the morning's trading. Many traders read the chain at the open for context and wait for it to settle before acting.
Late morning. Change in OI starts to mean something: strikes where writers are adding positions as the market moves show up clearly, and PCR for the day settles into a range.
Midday. The quietest hours. Theta keeps working, so short-dated premiums fall even if Nifty does not move, which is when the ATM straddle shrinks fastest on a calm day.
The last hour. Positions are closed or rolled, especially on expiry day. A large fall in OI at a strike in the last hour is often traders leaving, not a new view, and short-dated options can move sharply as gamma peaks.
Open interest is published at intervals during the session, so the OI columns move in steps while prices move continuously. Compare like with like: today's late-morning chain with yesterday's late-morning chain, and the day's closing OI with the previous close.
Strikes by delta
Delta is the most consistent way to compare strikes across different market levels, because "the 0.20 delta call" means roughly the same risk whether Nifty is at 22,000 or 26,000. A model chain with Nifty at 25,000 and a week to expiry might show:
| Call strike | Delta | Put strike | Delta |
|---|---|---|---|
| 25,000 | 0.52 | 25,000 | −0.48 |
| 25,200 | 0.36 | 24,800 | −0.33 |
| 25,400 | 0.23 | 24,600 | −0.21 |
| 25,600 | 0.13 | 24,400 | −0.12 |
| 25,800 | 0.07 | 24,200 | −0.06 |
Put deltas fall a little more slowly than call deltas at the same distance, because of the skew. A seller choosing 0.20 delta on both sides ends up with strikes not quite the same distance from the spot. The figures are illustrations; the live chain shows the real ones.
Gamma exposure on the chain
The gamma exposure (GEX) view estimates, strike by strike, how much the dealers who sold the options would need to buy or sell Nifty futures to stay hedged as the index moves. Where their net gamma is positive, their hedging tends to dampen moves: they buy dips and sell rallies. Where it is negative, hedging can add to moves. The zero-gamma level is the index price where the net figure changes sign. GEX rests on an assumption about who holds which side of each option, which no one can see, so read it as a rough map of where the market may be stickier or looser, not as a forecast of direction.
Charges and the chain
The premium on the chain is not what you keep. Every option trade pays brokerage, STT of 0.15% on the sell premium, exchange charges, stamp duty and GST. On one lot of a Nifty option bought at ₹100 and sold at ₹110 through a ₹20-per-order broker, the charges come to about ₹64, so the premium has to move about ₹1 just to cover them. That matters most for cheap far strikes and small targets, where a rupee is a large share of the premium. Check the bid-ask spread too: crossing a ₹1 spread on entry and exit costs as much as the charges.
The chain and the chart
The chain and the chart answer different questions. The chart shows where Nifty has been and where buyers and sellers met; the chain shows how traders are positioned for where it goes next and what that positioning costs. Reading them together is more useful than either alone: a level on the chart that lines up with heavy open interest on the chain is one more traders are watching, and a breakout on the chart through a strike where calls are being covered has more fuel than one where calls are still being written.
Nifty, Bank Nifty and Sensex chains
| Nifty | Bank Nifty | Sensex | |
|---|---|---|---|
| Exchange | NSE | NSE | BSE |
| Weekly expiry | Yes, Tuesday | No, monthly only | Yes, Thursday |
| Lot size (from January 2026) | 65 | 30 | Set by BSE |
| Strike interval | 50 points | 100 points | 100 points |
The same reading applies to each chain. Bank Nifty's moves are larger in points and its options carry higher IV; Sensex options expire on a different weekday, which gives traders a second weekly expiry. The Bank Nifty guide in the related list below covers that chain.
QuantPower's option chain
QuantPower's option chain is free to use and shows open interest, change in OI, IV and Greeks for every strike, with views for price, Greeks, OI and volume, the straddle, gamma exposure and a custom set of columns. An analytics panel shows the put-call ratio, max pain, call and put walls, the ATM straddle with the expected move, and the zero-gamma level, refreshed through the session. Beside the chain, Nifty's futures show their price, open interest and buildup label. Prices come from your connected broker account, so they match your broker's terminal; connect your broker to see the live chain. From any strike you can buy or sell through the order sheet, add legs and see their payoff, and move the legs into the strategy builder to add entries, stops and exits.
A short checklist before trading from the chain
- Expiry. Is this the expiry you meant, and how many days are left?
- ATM and the straddle. Where is the money, and how big a move is priced?
- Liquidity. Are the spreads on every strike you will trade tight enough, and is there volume?
- Open interest. Where are positions heaviest, and where are they changing today?
- IV. Is it high or low for this expiry, and how does the skew look?
- Your levels. At what Nifty level is the trade wrong, and what will it cost to be there?
- Size and margin. Does the loss at that level fit your budget, and does the margin fit with room to spare?
Seven questions take two minutes on the chain. Most expensive mistakes in options come from skipping one of them.
Common mistakes
- Trading illiquid strikes with wide spreads.
- Reading high OI as a guaranteed level. Large positions get rolled, covered or overrun.
- Ignoring IV when choosing between buying and selling.
- Using LTP as the trade price. The price you can trade at is the bid or the ask.
- Mixing expiries when comparing OI or PCR.
- Using old habits after rule changes. Expiry days, lot sizes and the indices with weekly options have all changed since 2024.
Where option chain reading is going
The chain has moved from a page of numbers to a working screen. Summaries such as the expected move, gamma exposure and buildup labels now sit beside the raw columns, and traders can act on a strike without leaving the chain. The next step is in how the reading is used: written down as rules, tested on past expiries and checked in a Forward test before real money follows it. The chain itself stays what it always was, a record of what traders hold and what the market charges, read by someone who decides what to do with it.
Start with 500 free tokens
Connect your broker, build a strategy and test it on paper before a single live order goes out.
Frequently asked questions
What is the Nifty option chain?
A table of all Nifty call and put options for an expiry, showing each strike's price, volume, open interest, implied volatility and Greeks.
How do I read the option chain for intraday trading?
Find the ATM strike, check the bid-ask spreads, look at where OI and change in OI are concentrated, and compare IV across strikes. Use this as context for a planned trade, not as a signal on its own.
What does high OI at a strike mean?
That many contracts are open at that strike. Above the market on calls, many traders read it as resistance; below the market on puts, as support.
Why are put IVs higher than call IVs?
Because of skew: demand for downside protection makes out-of-the-money puts more expensive, which shows as higher IV.
Is the option chain data real time?
In QuantPower, yes. The chain shows prices from your connected broker account during market hours, so they match your broker's terminal. Public option chains on exchange or news websites are often delayed by a few minutes.
Why does open interest on the chain change in steps?
The exchange publishes open interest at intervals during the session rather than with every trade, so the OI columns update in steps while prices move continuously. The day's final figure, after the close, is the one to compare from day to day.
Related guides
- Option chain analysis: reading any option chain step by step
- Option chain tutorial: navigating QuantPower's chain
- Bank Nifty option chain: the same reading for Bank Nifty
References
- NSE, equity derivatives contract specifications and history: Nifty options from 4 June 2001, Nifty weekly options from February 2019 (nseindia.com)
- SEBI, circular "Measures to strengthen Equity Index Derivatives framework for increased investor protection and market stability", 1 October 2024 (sebi.gov.in)
- NSE, circular on the revision of expiry days of derivatives contracts, effective 1 September 2025 (nseindia.com)
- NSE, revision in market lot of index derivative contracts from the January 2026 series (nseindia.com)
- NSE, India VIX (nseindia.com)
- Sheldon Natenberg, *Option Volatility and Pricing*, second edition (2014)