For example, ₹10,000 a month for 15 years at an assumed 12% a year grows to an estimated ₹47,59,314 on ₹18,00,000 invested. Run as a SIP in shares through a ₹20-per-order broker and sold in one tax year, about ₹43.71 lakh of it is left after charges and tax. The calculator shows each of these steps: the growth, the charges on every buy and the final sale, and the tax, so the figure you plan with is the one you would actually keep. It is a planning tool, not a forecast: the return you enter is an assumption, and the most useful thing you can do with it is try a lower one too.
How to use the SIP calculator
- Pick a mode: SIP for a fixed instalment, Step-up SIP for one that rises every year, or Goal to work out the instalment a target needs.
- Choose monthly or weekly instalments.
- Enter the amount, the expected return a year and the time period. A lump sum at the start is optional.
- Switch between future rupees and today's money to see the effect of inflation.
- Under Run it as a stock or ETF SIP, choose shares or an equity ETF, your broker, and whether you sell at the end.
- Copy the link to save or share the plan.
A short history of the SIP in India
Investing a fixed sum at regular intervals is an old idea. Savings schemes in which a family put aside the same amount every month were common long before mutual funds, and the recurring deposit at a bank works the same way with a fixed interest rate. What the systematic investment plan added was the market: the same monthly amount buys units of a fund at whatever price they stand that month.
India's mutual fund industry began with the Unit Trust of India in 1964 and opened to other fund houses from 1987 and to private ones from 1993.1 SIPs grew with the private funds in the 1990s and 2000s, and the industry body AMFI later made them the centre of its "Mutual Funds Sahi Hai" campaign, which began in 2017.2 Electronic mandates and later UPI autopay made a monthly debit almost effortless.
The numbers since then are large. By August 2026 the number of contributing SIP accounts had passed 10 crore, and in September 2026 SIP contributions reached a record ₹32,490 crore in a single month, according to AMFI's monthly data.3 Alongside fund SIPs, cheap online broking brought SIPs in shares and ETFs, which buy on the exchange and hold in the investor's own demat account. India's first exchange traded fund, on the Nifty, was launched at the end of 2001.4 A SIP in an ETF combines the habit of a fund SIP with the low running cost of an index fund, but it pays exchange charges and brokerage on every buy, which is why this calculator shows them.
How the SIP calculator works
A SIP puts the same amount into the market at a fixed interval. Each instalment grows for as long as it stays invested: the first one for the whole period, the last one for a single month. The SIP calculator adds up those instalments at the return you assume.
The last factor, (1 + i), is there because each instalment goes in at the start of its month and earns that month's growth. Many calculators set i to the annual return divided by 12. At 12% that is 1% a month, which compounds to 12.68% a year and lifts the result by about 6% over 15 years: ₹50,45,760 instead of ₹47,59,314 for the same inputs. This SIP calculator converts the annual rate exactly, so 12% means 12%. Switch to the ÷ 12 method under Assumptions to compare with other tools.
How time changes the result
The longer a SIP runs, the larger the share of the final value that comes from growth rather than from what you put in. At an assumed 12% a year, ₹5,000 a month grows like this:
| Years | You invest | Estimated value | Growth as a share of the value |
|---|---|---|---|
| 10 | ₹6,00,000 | ₹11,20,179 | 46% |
| 20 | ₹12,00,000 | ₹45,99,287 | 74% |
| 25 | ₹15,00,000 | ₹85,11,033 | 82% |
| 30 | ₹18,00,000 | ₹1,54,04,866 | 88% |
Doubling the period from 10 to 20 years doubles what you put in but roughly quadruples the estimated value. That is compounding: the growth itself earns growth. It is also why the assumed return matters so much over long periods, and why a SIP that stops early gives up the years in which most of the growth would have come.
How the assumed return changes the result
The same ₹10,000 a month for 15 years, at four assumed returns:
| Assumed return a year | Estimated value | Growth |
|---|---|---|
| 8% | ₹33,97,785 | ₹15,97,785 |
| 10% | ₹40,16,212 | ₹22,16,212 |
| 12% | ₹47,59,314 | ₹29,59,314 |
| 15% | ₹61,63,656 | ₹43,63,656 |
A few points of return change the result by lakhs. No one knows the return of the next 15 years, so plan with a figure you would be content to be wrong about on the low side. The rates in this table are assumptions for illustration, not expected returns from any investment.
Step-up SIP calculator
A step-up SIP raises the instalment once a year, usually in line with salary. Choose Step-up SIP and set the yearly increase. The amount stays the same for 12 months, then rises by the percentage you set.
Start at ₹10,000 a month and raise it 10% a year for 15 years at 12%. The instalment reaches ₹37,975 a month in the final year. You invest ₹38,12,698 and the estimated value is ₹82,74,718, against ₹47,59,314 for a flat ₹10,000 SIP.
A step-up does two things: it puts more money in, and it keeps the instalment's real value from shrinking as prices rise. A flat ₹10,000 a month buys less every year at 6% inflation; a 10% yearly step-up more than keeps pace.
Target SIP calculator: the amount for a goal
Goal mode works backwards. Enter what the goal costs today, the years until you need it and the inflation you expect. The calculator raises the goal to its future cost, takes off what your existing savings will grow to, and shows the instalment that covers the rest, rounded up to the next ₹10.
A goal that costs ₹50 lakh today and is 15 years away costs about ₹1.20 crore at 6% inflation. At an assumed 12% a year, that needs ₹25,180 a month, or ₹14,490 a month to start with a 10% yearly step-up.
Goals with a fixed date need a plan for the last few years. A market fall in the year before a child's college fees are due can leave the plan short at the worst moment. Many investors move the money for a near goal into steadier investments over its final two or three years; the calculator's "today's money" view helps to see how much that will be.
Worked goals
Goal mode turns a target into a monthly figure. Three common goals, with assumptions stated so you can change them:
| Goal | Assumptions | Monthly SIP needed |
|---|---|---|
| A child's education | Costs ₹25 lakh today, needed in 12 years; education costs rise 7% a year, so about ₹56.3 lakh then; assumed return 11% a year | About ₹19,520 |
| Retirement | ₹3 crore needed in 25 years; assumed return 11% a year | About ₹20,650 |
| A home down payment | ₹20 lakh needed in 5 years; assumed return 8% a year, since five years is short for a share-heavy plan | About ₹27,250 |
Two things stand out. The shorter the time, the more of the goal you must fund yourself, which is why the down payment needs more each month than the retirement plan for a far smaller sum. And the return you assume for a short goal should be lower, because a fall near the end leaves no time to recover.
What starting later costs
Two investors put ₹10,000 a month into the same plan at an assumed 11% a year until they turn 60. One starts at 25 and invests for 35 years; the other starts at 35 and invests for 25 years. The first puts in ₹42 lakh and ends with about ₹4.34 crore. The second puts in ₹30 lakh and ends with about ₹1.45 crore. Ten more years of ₹10,000 a month, ₹12 lakh in all, accounts for nearly ₹2.9 crore of the difference, because the money invested earliest compounds longest.
Reading the result
The calculator shows several figures. Each answers a different question:
| Figure | What it tells you |
|---|---|
| Invested | The total of your instalments and any starting lump sum |
| Estimated value | What the plan is worth at the end, at the return you assumed |
| Estimated growth | Value minus invested |
| Value in today's money | The value divided by inflation over the period |
| Charges | Brokerage, STT, stamp duty, exchange and SEBI fees and GST on every buy, and on the sale if you choose to sell |
| Tax | Capital gains tax on the sale, worked out instalment by instalment |
| Left after charges and tax | What you would keep if you sold everything at the end |
| Year-by-year table | Invested, value and growth at the end of each year |
The year-by-year table is the most useful figure for checking a plan. If you might need the money early, read the row for that year, not the last one.
When to pause, stop or change a SIP
A SIP works because it runs through good markets and bad, but plans change. Some fair reasons to change one:
- Your income changes. A step-up when it rises, a smaller instalment when it falls. A smaller SIP that continues beats a larger one that stops.
- A goal comes near. Over the last two or three years before a fixed-date goal, many investors move new instalments, and gradually the money already invested, into steadier investments.
- The costs are too high. If brokerage takes more than a fraction of a per cent of each instalment, move to a cheaper broker, fewer and larger instalments, or an ETF.
- The holding no longer fits. A stock you bought for its business may change; an index ETF rarely needs replacing.
A fall in the market on its own is rarely a reason to stop. It is when a fixed instalment buys the most units. If a fall worries you, look at the plan's horizon rather than its latest value: money not needed for ten years has ten years in which the prices of today's instalments matter far less than the habit of making them.
Rupee cost averaging, with numbers
A fixed instalment buys more units when the price is low and fewer when it is high. Over time that brings the average cost per unit below the simple average of the prices paid. Here is a six-month illustration with ₹5,000 a month into a fund whose price moves from ₹100 down to ₹80 and back up:
| Month | Price | Units bought |
|---|---|---|
| 1 | ₹100 | 50.00 |
| 2 | ₹90 | 55.56 |
| 3 | ₹80 | 62.50 |
| 4 | ₹95 | 52.63 |
| 5 | ₹105 | 47.62 |
| 6 | ₹110 | 45.45 |
| Total | 313.76 |
You invest ₹30,000 for 313.76 units, an average cost of about ₹95.61 a unit, below the simple average price of ₹96.67. At the final price of ₹110 the holding is worth about ₹34,514. The prices are an illustration. Averaging lowers the cost of buying through a fall; it does not protect against a fall that does not recover, and in a market that only rises a lump sum at the start does better.
A SIP in shares buys whole shares only, so each instalment buys the largest whole number of shares the amount allows, and what is left over waits for the next instalment or is not spent. The fewer shares an instalment buys, the less even the averaging.
Monthly or weekly?
Switch How often to Weekly to compare. The same yearly amount split into weekly instalments ends very close to the monthly result, because each week's money goes in a little earlier or later:
| Plan | You invest over 15 years | Estimated value at 12% |
|---|---|---|
| ₹10,833 a month | ₹19,50,000 | about ₹51.56 lakh |
| ₹2,500 a week | ₹19,50,000 | about ₹51.37 lakh |
The real difference is in the charges. A weekly plan in shares places 52 orders a year instead of 12, so brokerage charged per order adds up more than four times as fast. Weekly suits a broker that charges nothing for delivery orders; with ₹20 an order, monthly is usually cheaper.
SIP returns calculator vs the returns you get
Every SIP returns calculator, this one included, assumes the same return in every year. Real prices move up and down, so the value of a SIP on a given date can be well above or below the estimate, and it can be below what you put in. The assumed rate drives the result more than any other input, so try a lower figure as well as the one you expect.
To measure what an existing SIP has earned, you need the date and amount of each instalment and today's value. The annual rate that links those cash flows is called XIRR, and a spreadsheet's XIRR function works it out.
What a stock or ETF SIP costs
A mutual fund SIP buys units at the fund's price with no charge per order. A SIP in shares or ETFs places a delivery order each time, so the usual charges apply, and you pay tax on the gain when you sell. The SIP calculator includes both.
| Charge | Shares | Equity ETF |
|---|---|---|
| Brokerage | ₹0 to ₹20 an order, by broker | Same |
| STT | 0.1% on buy and on sell | Nil on buy, 0.001% on sell |
| Stamp duty | 0.015% on buy | 0.015% on buy |
| Exchange and SEBI fees | About 0.003% of each order | Same |
| GST | 18% on brokerage and fees | Same |
| Tax when you sell | 20% on gains held up to 12 months; 12.5% on longer-held gains above ₹1.25 lakh a year; plus 4% cess | Same for equity ETFs |
Take ₹10,000 a month for 15 years at 12%. In shares through a broker charging ₹20 an order, the plan pays about ₹6,385 in buy charges over 180 orders, ₹4,943 to sell, and about ₹3.66 lakh in tax if everything is sold in one tax year, leaving about ₹43.71 lakh. In an equity ETF with ₹0 brokerage, buy charges fall to about ₹337 and selling costs about ₹226, leaving about ₹43.89 lakh.
Brokerage per order weighs most on small, frequent instalments. A weekly ₹2,500 SIP in shares at ₹20 an order pays about ₹20,723 in buy charges over 15 years. The charges on a single order are worked out line by line in the brokerage calculator, and the securities transaction tax alone in the STT calculator.
Mutual fund SIP or stock and ETF SIP?
| Mutual fund SIP | Stock or ETF SIP | |
|---|---|---|
| What it buys | Units of a fund, at the day's NAV | Shares or ETF units on the exchange, at the market price |
| Where it is held | With the fund house, or in demat | In your own demat account |
| Charges per instalment | None per order; the fund's expense ratio is taken daily | Brokerage, STT on shares, stamp duty, exchange fees and GST |
| Fractions | Fractional units | Whole shares only |
| Who chooses the stocks | The fund manager, or the index for an index fund | You, or the index for an ETF |
| Tax on equity gains | The same rules for equity funds and shares | The same rules |
A stock or ETF SIP suits an investor who wants to own the shares directly, choose them himself, or hold a low-cost index ETF in his own demat account. A fund SIP suits one who wants the choices made for him and fractional units.
Run it as a stock SIP in QuantPower
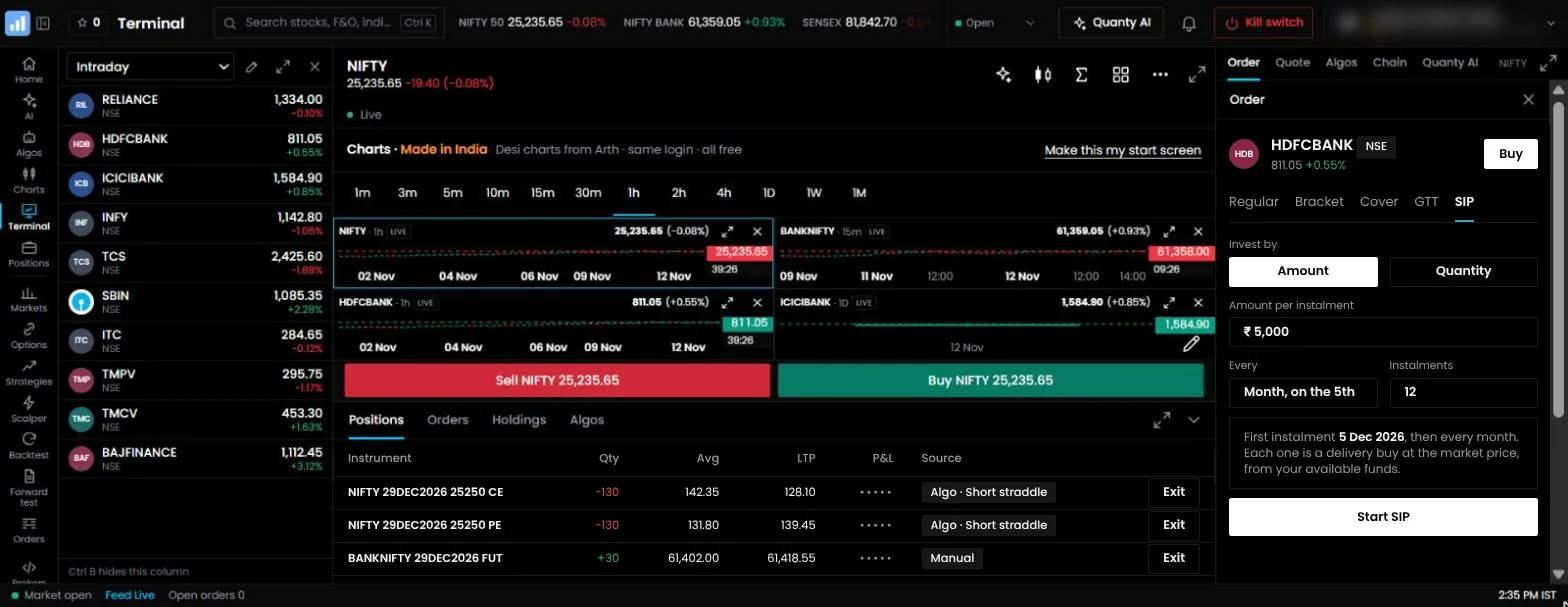
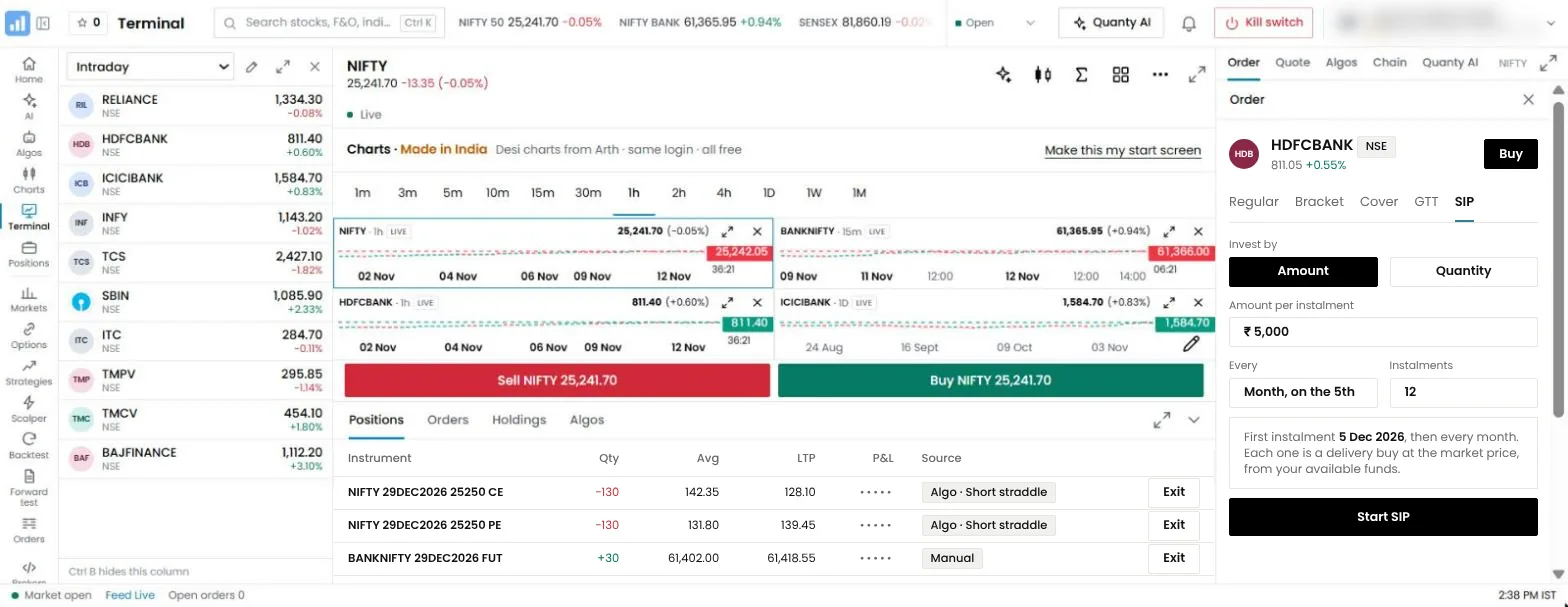
QuantPower runs a stock SIP in shares and ETFs through your connected broker account, weekly or monthly, for one stock or several in one plan. On each due date it prepares a delivery buy at the market price; in reminder mode you place it with one tap, and in auto mode it is placed for you a few minutes after the market opens. Stock orders are in whole shares, so each instalment can differ slightly from the amount you set. Stock SIPs cost no tokens; your broker's charges apply as to any order. See pricing.
Five questions to answer before you start
What is the money for? A SIP without a purpose is easy to stop at the first fall. One tied to a goal, a date and an amount is easier to keep. Write the goal down, even roughly, and use Goal mode to see what it needs.
When will you need it? Money needed within three to five years is exposed to a fall at the wrong moment. The longer the horizon, the more a share or index SIP can do, and the more the averaging has time to work.
What return are you assuming, and why? Pick a figure you can defend, then run the calculator again two or three points lower. If the plan still works at the lower figure, it is a sound plan. If it only works at the higher one, it depends on luck.
What will it cost you? Add up the brokerage and charges per instalment for your broker and your instrument. For a SIP in shares at a broker charging per order, a larger monthly instalment usually costs less, in per cent, than several small weekly ones.
What will make you stop? Decide in advance. A change of income, a goal that has been met, or a holding that no longer fits are reasons. A bad month in the market is not, because that is when the instalment buys the most.
A worked year in an index ETF
Take ₹5,000 on the 5th of every month into a Nifty ETF whose unit price starts the year near ₹260. In January the instalment buys 19 whole units for ₹4,940, and the ₹60 left over is not spent. In a month when the market has fallen and the unit is at ₹230, the same ₹5,000 buys 21 units for ₹4,830. Over twelve instalments, with prices moving between those levels, the plan buys about 240 units, more in the cheap months and fewer in the dear ones, at an average cost below the simple average of the twelve prices. The year's charges at a broker with no delivery brokerage come to a few rupees: stamp duty, exchange fees and GST on each buy, and no STT on buying an equity ETF.
Every unit stays in your own demat account. If you stop the SIP, the units stay where they are; nothing is redeemed unless you sell. That is one of the practical differences from a fund SIP: you own the ETF units directly and decide when to sell them, at the market price of that moment. Because only whole units are bought, the amount actually invested each month is a little below ₹5,000, and the calculator's estimate, which assumes every rupee is invested, will run slightly ahead of a real plan with a high unit price. The prices in this example are illustrations, not a view of any ETF.
Common mistakes when planning a SIP
- Planning with a high return. The difference between 12% and 15% over 15 years is about ₹14 lakh on ₹10,000 a month. Plan with the lower figure.
- Stopping in a fall. A SIP's averaging works only if the instalments continue when prices are low.
- Ignoring inflation. ₹47.6 lakh in 15 years is about ₹19.9 lakh in today's money at 6% inflation.
- Forgetting charges on small instalments. ₹20 brokerage on a ₹1,000 instalment is 2% before the investment has earned anything.
- Selling everything in one tax year. Spreading sales across tax years can use the ₹1.25 lakh long-term exemption more than once.
Where SIPs are going
SIPs have become the default way most Indian households invest in shares. The next changes are about cost and control: lower minimum instalments, cheaper delivery orders, more index ETFs, and SIPs in shares that live in the investor's own demat account and run on a schedule rather than on memory. The arithmetic does not change: the same amount, the same interval, and time doing most of the work.
Start with 500 free tokens
Connect your broker, build a strategy and test it on paper before a single live order goes out.
Frequently asked questions
Which monthly rate does this SIP calculator use?
It converts the annual return to an exact monthly rate, (1 + annual return)^(1/12) − 1, which is 0.949% a month for 12%. Many calculators divide by 12 instead, which shows a higher figure for the same inputs. Switch the method under Assumptions to compare.
Is a lump sum better than a SIP?
With one constant positive return, a lump sum always ends higher because all the money is invested for longer: ₹18 lakh invested at once for 15 years at 12% grows to about ₹98.5 lakh, against ₹47.6 lakh for ₹10,000 a month. Markets do not move at a constant rate. A SIP spreads purchases across many prices, which lowers the risk of putting everything in just before a fall, and it suits money that arrives each month.
How does the SIP calculator work out tax when I sell?
It treats each instalment separately. Units bought in the 12 months before the sale are short-term and taxed at 20%. Older units are long-term: the first ₹1.25 lakh of long-term gains in a tax year is exempt and the rest is taxed at 12.5%. 4% cess is added. It assumes you sell everything in one tax year and have no other gains. Confirm your own position with a tax professional.
Can I run a weekly SIP?
Yes. Switch How often to Weekly. QuantPower runs stock and ETF SIPs weekly or monthly through your connected broker. Weekly instalments mean more than four times as many orders, so brokerage charged per order adds up faster.
What does "today's money" mean in the result?
It divides the future value by the inflation you entered for every year of the plan, so you see what the sum would buy at today's prices. At 6% inflation over 15 years, a rupee then buys about what 42 paise buys now.
Related calculators
- Stock SIP: running a SIP in stocks and ETFs through your broker
- Compound interest calculator: a starting amount that grows with regular additions
- Stock profit calculator: the profit on a holding after charges and tax
References
- Securities and Exchange Board of India and AMFI, history of the Indian mutual fund industry: UTI 1964, public sector funds from 1987, private sector funds from 1993 (amfiindia.com)
- AMFI, "Mutual Funds Sahi Hai" investor awareness campaign, and the SIP value formula with instalments at the start of each period (mutualfundssahihai.com)
- AMFI monthly data: contributing SIP accounts above 10 crore in August 2026; SIP contributions of ₹32,490 crore in September 2026 (amfiindia.com)
- NSE, history of exchange traded funds in India: the first Nifty ETF, December 2001 (nseindia.com)
- Income-tax Act, 2025: capital gains on listed equity shares and equity-oriented funds for tax year 2026-27 (incometaxindia.gov.in)
- NSE: transaction charges; STT and stamp duty on delivery trades (nseindia.com)
- Zerodha, Upstox, Fyers, IIFL Capital and Wisdom Capital: published brokerage pages (checked 10 October 2026)