The option chain and the analytics are free in QuantPower: they cost no tokens. Prices come live from your own connected broker, at any of 100+ Indian brokers, including Wisdom Capital, Zerodha, Upstox, Fyers and IIFL Capital, and the orders you place go to that broker account. QuantPower is software, not a broker, and never holds your money. This page explains what each screen shows, how to read it, and how a reading on the chain becomes an order or a rule.
What the option trading app shows
| Part | What it shows |
|---|---|
| Option chain | Every strike of an expiry, calls on the left and puts on the right, with the spot price marked |
| Chain views | Price, Greeks, OI and volume, Straddle, GEX and a Custom set of columns, on the same rows |
| Greeks and IV | Delta, gamma, theta, vega and implied volatility for every strike |
| Analytics | Put-call ratio, max pain, call and put walls, the ATM straddle and its IV, the expected move and the zero-gamma level |
| Charts by strike | Open interest and change in OI, the IV smile, the straddle premium and gamma exposure (GEX) |
| Futures | Every listed expiry of the underlying's futures with live price, change, open interest and its buildup label |
| Underlyings | Nifty, Bank Nifty, Sensex and every stock in the F&O list, with stocks in the F&O ban marked |
| Orders | Buy or sell any strike from the chain, through your own broker |
| Price | Free: no tokens for the chain or the analytics |
A short history of option analytics
Options are old, but option analytics are recent. Contracts that gave the right to buy at a set price were traded in Amsterdam in the seventeenth century and in London and New York in the nineteenth, but there was no agreed way to price them. That changed in 1973. The Chicago Board Options Exchange opened that April as the first exchange for listed stock options, and in the same year Fischer Black and Myron Scholes published their model for pricing an option from the stock price, the strike, the time to expiry, interest rates and volatility.1 Robert Merton extended it the same year. The model gave traders the Greeks, the measures of how an option's price changes with each input, and it made implied volatility, the volatility a market price implies, the common language of option traders.2
The tools followed the model. Exchanges published open interest, the count of open contracts, and traders began to read it strike by strike. The put-call ratio became a popular gauge of how traders were positioned. In 1993 the CBOE launched its volatility index, the VIX, built from option prices.
India's listed options began with the NSE's index options on 4 June 2001, followed by stock options the next month.3 The NSE began publishing India VIX in 2008. Weekly options on Bank Nifty and then Nifty turned options into the most traded part of the Indian market. The rules have changed often since: on 1 October 2024 SEBI limited weekly expiries to one index per exchange, raised the minimum contract size, required option premiums to be collected upfront and began intraday monitoring of position limits, mostly from 20 November 2024.4 From 1 September 2025 the NSE moved its expiries to Tuesday.5 From the January 2026 series the Nifty lot became 65.6
Through all of it the chain has stayed the trader's main screen. What has changed is how much it shows. A chain that once showed price and open interest now shows the Greeks, implied volatility, the straddle premium and the gamma that market makers hold at each strike, and it updates live.
The option chain
Each row of the chain is one strike. Calls sit on the left of the strike column and puts on the right. The strike column stays put while each side scrolls sideways, and a line marks where the spot price sits between strikes. Bars on the open-interest columns show at a glance where positions are largest.
The columns change with the view you pick:
| View | Columns |
|---|---|
| Price | Last price, bid and ask, change |
| Greeks | Delta, gamma, theta, vega and implied volatility |
| OI and volume | Open interest, change in OI and volume |
| Straddle | The call and put premium added together at each strike |
| GEX | The gamma exposure at each strike |
| Custom | The columns you choose |
Tap a row and Buy and Sell buttons appear on that row. Each opens the order sheet for that strike with the chain's quantity. One chain-wide quantity setting is used by the chain's buttons and by the Scalper, so you set your lot size once.
| Column | What it tells you |
|---|---|
| Last price, bid and ask | What the option trades at, and the spread you pay to get in and out |
| Volume | How many contracts traded today |
| Open interest (OI) | How many contracts are open at that strike |
| Change in OI | Whether positions are being built or closed today |
| Implied volatility (IV) | The volatility the option's price implies |
| Delta | How much the option moves for a 1-point move in the underlying |
| Gamma | How fast delta changes |
| Theta | What the option loses in a day if nothing else changes |
| Vega | What the option gains or loses for 1 point of IV |
A chain row by row
This is a model Nifty chain with the index at 25,000, 12 days to expiry and IV of 14%, priced with the Black-Scholes model. It shows how the Greeks change across strikes. Live prices differ.
| Strike | Call price | Call delta | Call theta a day | Put price | Put delta | Put theta a day |
|---|---|---|---|---|---|---|
| 24,800 | ₹398.30 | 0.66 | −₹12.55 | ₹145.35 | −0.34 | −₹8.15 |
| 24,900 | ₹336.35 | 0.60 | −₹12.83 | ₹183.20 | −0.40 | −₹8.40 |
| 25,000 | ₹280.50 | 0.54 | −₹12.85 | ₹227.10 | −0.46 | −₹8.40 |
| 25,100 | ₹230.85 | 0.48 | −₹12.61 | ₹277.30 | −0.52 | −₹8.15 |
| 25,200 | ₹187.50 | 0.41 | −₹12.11 | ₹333.70 | −0.59 | −₹7.64 |
Read across a row and you see the trade-offs. The 25,000 call costs ₹18,232.50 a lot of 65, moves about ₹35 for each Nifty point (0.54 × 65), and loses about ₹835 a day to time decay (12.85 × 65). Its vega is 18.00, so one point of IV is worth ₹1,170 a lot. Read down a column and you see the shape of the chain: delta falls steadily as strikes move up, and theta is largest near the money, where time value is largest. The option greeks guide explains each measure with Nifty examples.
The analytics screen
The analytics screen reads the whole chain at once and turns it into a few numbers and charts. It refreshes every 30 seconds. Tap any chart and the strike under your finger is picked on every chart and read out above it, so you can follow one strike across open interest, IV and gamma.
Put-call ratio
The put-call ratio (PCR) divides the open interest of all puts by the open interest of all calls for the expiry. A ratio above 1 means more puts are open than calls; below 1, more calls. Traders read it in two opposite ways: as a sign of fear when puts are heavy, or as a sign of support, because put writers are often the ones adding those puts. The Nifty PCR guide works through a model chain with exact figures, including how the ratio moves during a session.
Max pain
Max pain is the strike at which option buyers as a group would lose the most, and option writers would pay out the least, if the index settled there at expiry. It is worked out from the open interest at every strike. Some traders watch it on expiry day, on the idea that the price drifts towards it. Treat it as a description of where open interest sits, not as a target.
Call and put walls
The call wall is the strike with the largest call open interest, and the put wall the strike with the largest put open interest. They show where writers are most exposed. Traders often watch them as resistance above and support below, and watch the change in OI near them more closely than the total.
The ATM straddle and its IV
The at-the-money straddle is the price of the call plus the put at the strike nearest the spot. It is the market's price for a move of any direction before expiry. The screen shows it with its implied volatility, and the straddle chart shows how the straddle premium changes across strikes.
Expected move

The expected move turns the at-the-money straddle into a price range. The chain shows it for the chosen expiry as points and as a per cent of the spot, with the upper and lower prices marked on the strike ladder: the spot plus and minus the straddle premium. It is the size of move the option prices imply before expiry, not a forecast of direction or a limit on the move. Index options often close within it, and the days they do not are the days that matter most to an option seller, so read it as the market's estimate, with its misses.
IV smile
The IV smile plots implied volatility against strike. In Indian index options, puts below the spot usually carry a higher IV than calls the same distance above, because traders pay more for protection against a fall. A smile that steepens shows rising demand for that protection.
Gamma exposure and the zero-gamma level
Gamma exposure (GEX) estimates how much the market makers who sold the options would have to buy or sell the underlying to stay hedged as it moves, strike by strike. Where their net gamma is positive, their hedging tends to slow moves down. Where it is negative, hedging can speed moves up. The zero-gamma level is the price at which the net gamma changes sign. GEX rests on an assumption about who holds which side, so read it as a rough map of where moves may slow or quicken, not as a forecast.
Open interest and change in OI by strike
Two mirrored bar charts show calls to the left of each strike and puts to the right, for open interest and for today's change in it. The total shows where positions sit. The change shows what traders did today, which usually matters more.
Calls and puts never rely on colour alone on these charts: calls are always on the left, the put line is dashed, and every series is labelled.
Futures beside the chain
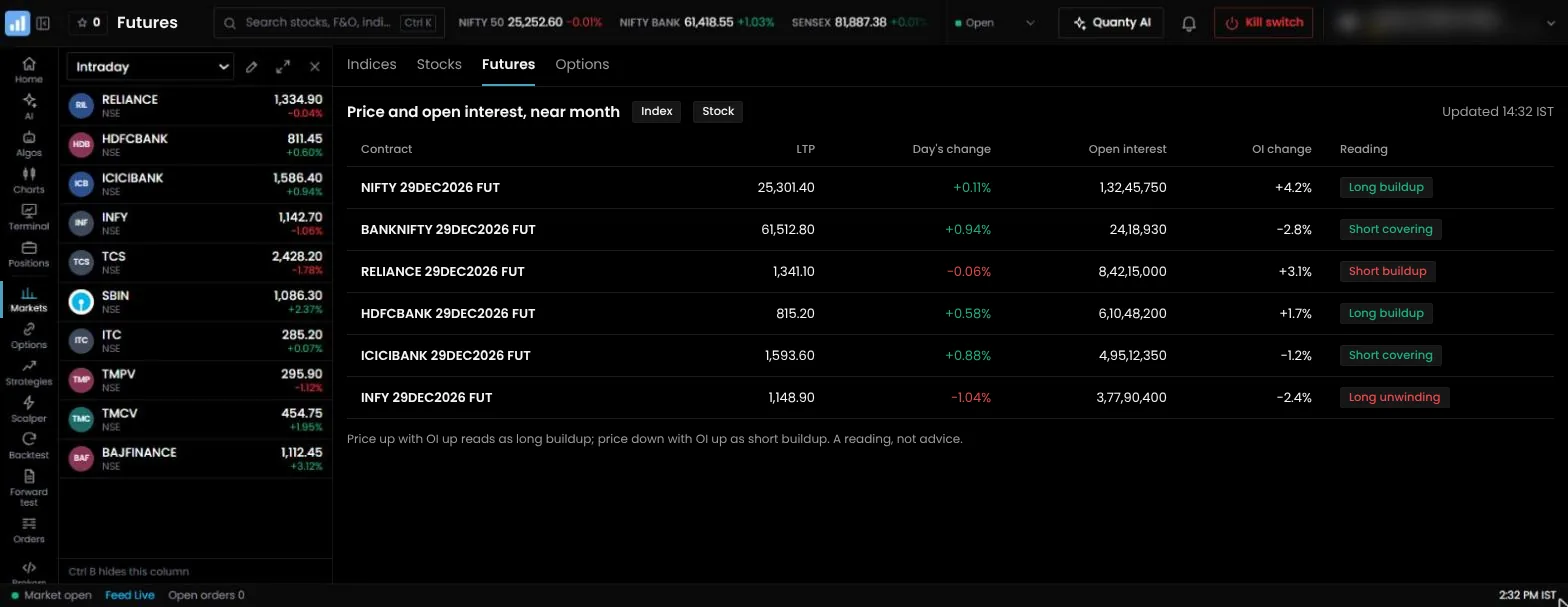
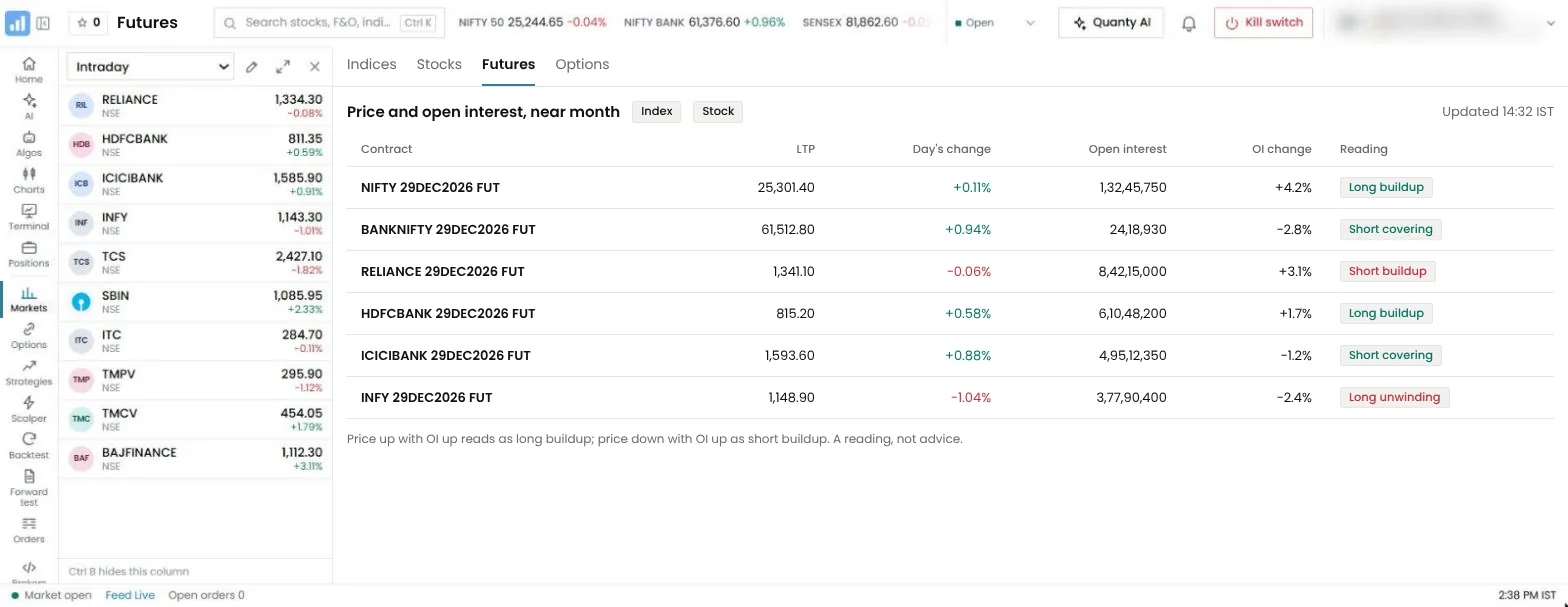
Next to the chain, the futures view lists every listed expiry of the same underlying, with its live price, change, open interest and buildup label: long buildup, short buildup, short covering or long unwinding, worked out from the price change and the open interest change since the previous day. The same label sits beside the futures price above the strikes, so you see how futures positions moved without leaving the chain. Buy and Sell open the order sheet on that contract. Comparing the futures price with the spot shows the premium the market is paying to hold the index to expiry, and the futures open interest shows whether new positions are coming in as the price moves.
From the chain to an order
- Pick the strike. Tap its row on the chain. Buy and Sell appear on that row.
- Check the order. The order sheet opens with the strike and the chain's quantity. It shows the margin before you send.
- Send it. The order goes to your connected broker account. Market, limit, SL and SL-M orders are available, and a large order can go as an iceberg, split into 2 to 50 legs sent one at a time.
- Build a strategy instead. For several legs, open the option strategy builder: add the legs, see the payoff, the break-evens and the margin, and send them together or turn them into an algo.
- Watch it live. Your positions show live profit and loss, and the account's daily loss limit, kill switch and Smart Exit cover every position.
The analytics screens stay the same whether you trade by hand or with an algo. An algo uses the same chain to pick its strikes, by rules such as at the money, a number of strikes away, a premium or a delta.
A worked example: reading the chain before an expiry-day trade
It is expiry morning. Nifty is near 25,000.
- Open the analytics screen. The put wall is at 24,800 and the call wall at 25,300. Max pain is 25,000. The PCR is near 1.
- Look at today's change in OI. Since the open, put OI at 24,900 has grown sharply while call OI at 25,200 has fallen. Writers are adding puts below the spot and covering calls above it.
- Check the straddle. The ATM straddle at 25,000 costs about 140 points. That is the market's price for the move to the close.
- Check the IV smile. Put IV below 24,900 is a little higher than call IV the same distance above, the usual shape.
- Decide what the chain says and what it does not. The chain shows where positions sit and how they changed today. It does not say where Nifty will close. Any trade still needs your own rule: an entry, a stop and an exit.
A worked example: choosing strikes for an iron condor
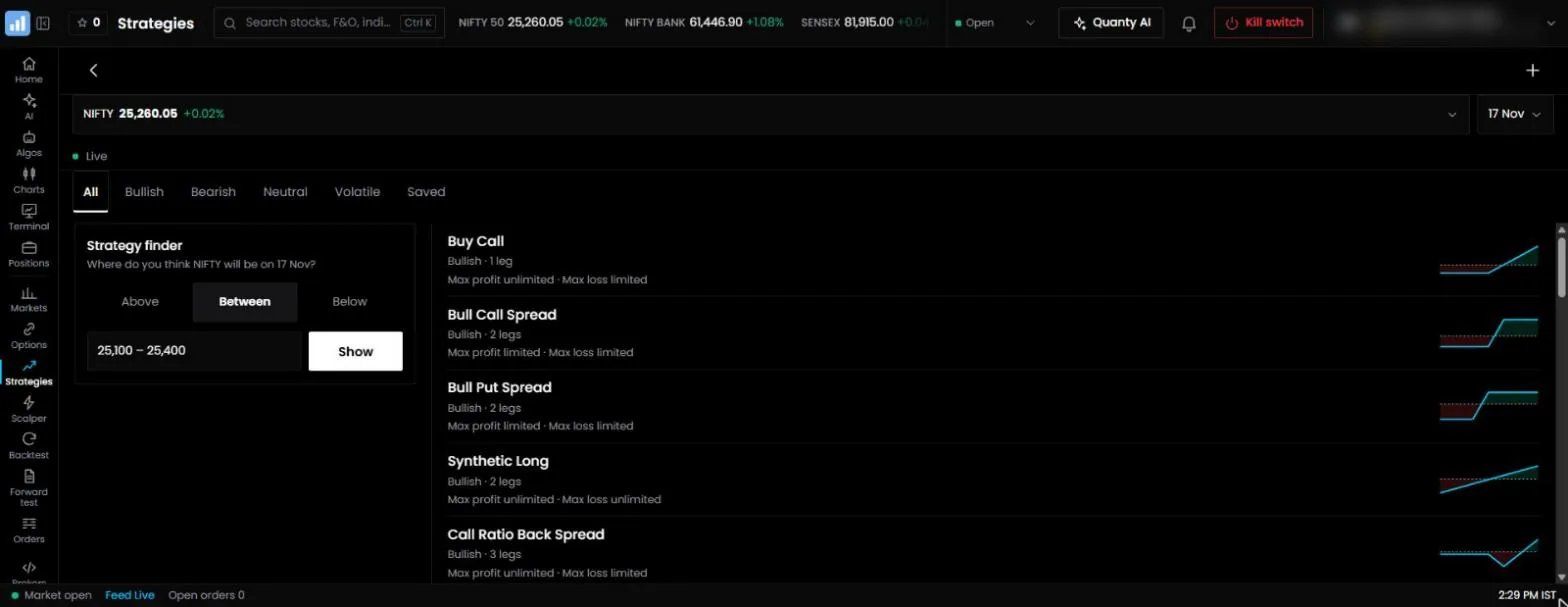
You want to sell an iron condor on next week's expiry, outside the range the chain suggests.
- Find the walls. The call wall is 25,500 and the put wall 24,500.
- Use delta to place the sold legs. In the Greeks view, find the call and put with a delta near 0.20 and −0.20. Suppose they are 25,400 and 24,600.
- Add the wings. Buy the 25,600 call and the 24,400 put to cap the risk.
- Open the strategy builder. Check the payoff, the two break-evens, the maximum loss and the margin your broker will block.
- Test it. Run it in Forward test for a few expiries before you trade it with real money, or set it up as an algo with strikes picked by delta at each entry.
Index options and stock options
The chain works the same way for every underlying, but what you read from it differs.
Nifty and Sensex carry the weekly expiries, one on each exchange since November 2024. Their chains are deep, with tight spreads near the money and open interest spread across many strikes. Weekly expiry day is when theta and gamma are largest, so the straddle and GEX views matter most on that day.
Bank Nifty now has monthly expiries only on the NSE. Its moves are larger in points than Nifty's, so the same delta means a larger rupee move per lot, and strike gaps are wider. Read the walls and the straddle in that light.
Stock options are monthly. Their chains are thinner: fewer strikes trade actively, and spreads widen quickly away from the money. Check the bid and ask before you pick a strike, because a stock option with a wide spread can cost several per cent of its premium just to enter and exit. A stock in the F&O ban is marked on the stocks list. During a ban, new positions in that stock's derivatives are not allowed; only positions that reduce existing open interest can be traded.
| Underlying | Expiries | What to watch most |
|---|---|---|
| Nifty | Weekly and monthly | Straddle, GEX and change in OI on expiry day |
| Sensex | Weekly and monthly | The same, on the BSE's own expiry day |
| Bank Nifty | Monthly | Larger point moves per delta; wider strike gaps |
| Stock options | Monthly | Bid-ask spread; F&O ban status; results dates |
The chain on a phone
Most option trades in India are now placed from a phone, so the chain is built for one. Each side scrolls sideways while the strike column stays fixed, so you never lose track of which strike you are on. The views replace a wide table with a few columns at a time: open Greeks when you are choosing a strike, OI and volume when you are reading positioning, Straddle when you are pricing a move. A tap on a row brings up Buy and Sell on that row only, so a stray tap elsewhere does nothing.
On the analytics screen, the charts by strike are sized for a phone too. Tap a chart and the strike under your finger is read out above it and picked on every other chart, so you can compare one strike's open interest, IV and gamma without switching screens.
The chain and the Scalper
For fast option trades, the Scalper puts the call and the put chart for a strike side by side, with a strike stepper, the margin shown before you send, and the kill switch at hand. It uses the same chain-wide quantity as the chain, so the lot you set once applies on both screens. A typical flow is to pick the strike on the chain, using its Greeks and open interest, and then trade it from the Scalper, where your order and position lines sit on the option's own chart.
How to use the analytics well
- Read change in OI before total OI. The total includes positions built weeks ago.
- Check the spread. A strike with a wide bid-ask spread costs you on the way in and on the way out.
- Price the move before the direction. The straddle shows what the market expects. A trade that needs a larger move than the straddle implies is a bet against the market's price.
- Use delta to size, not only to pick. Delta times lot size is the rupee move per point. Add it up across legs before you trade.
- Watch theta on expiry week. Time decay speeds up as expiry nears, for buyers and sellers alike.
- Do not trade one number. PCR, max pain and GEX each describe positioning. None of them is a signal on its own.
Common mistakes
- Treating max pain as a target. It shows where open interest sits, not where the index must settle.
- Reading the PCR one way only. A high PCR can mean fear or support, depending on who is adding the puts.
- Ignoring IV when buying. A cheap-looking option with high IV can lose value even if the index moves your way, once IV falls.
- Forgetting the lot size. Nifty lots changed in 2024 and again in 2026. Rupee figures from old notes may not apply.
- Selling options without a stop. One sharp move can take back many days of premium. Set a stop on each leg and an account-level loss limit.
Who uses the analytics
- Option buyers check IV and theta before paying a premium, and the straddle before choosing a strike.
- Option sellers watch change in OI near their strikes, the walls and the expiry-day margin.
- Futures traders compare futures open interest and price change to see whether a move is backed by new positions.
- Algo traders use the same chain to set the rules by which an algo picks its strikes.
- Investors who hold shares use the chain to price a protective put or a covered call on a stock they own, and check the spread before they trade it.
Choosing an option trading app
There is no single best app for option trading. It depends on how you trade. These are the points that separate the choices:
| Check | Why it matters | In QuantPower |
|---|---|---|
| Live Greeks and IV per strike | You price risk before you trade | Yes, on every strike |
| Change in OI, not only OI | Shows what is happening today | Yes, in the chain and by strike |
| PCR, max pain, walls and GEX | Positioning across the whole expiry at a glance | Yes, on the analytics screen |
| Orders from the chain | Fewer steps between idea and order | Yes, through your own broker |
| Payoff and margin before the order | You see the worst case first | Yes, in the strategy builder |
| Account-level loss limit | One rule protects every position | Yes: daily loss limit, kill switch and Smart Exit |
| Automation | Rules run without you at the screen | Yes, as algos on your broker account |
| Broker choice | You keep your broker | 100+ Indian brokers |
| Devices | Trade where you are | Web and Android |
If you trade a few options by hand with one broker, your broker's own app may be enough. An analytics platform earns its place when you trade several strategies, want the same view across brokers, or plan to automate. The options trading platform page covers the rest of QuantPower around the chain.
Brokers and data
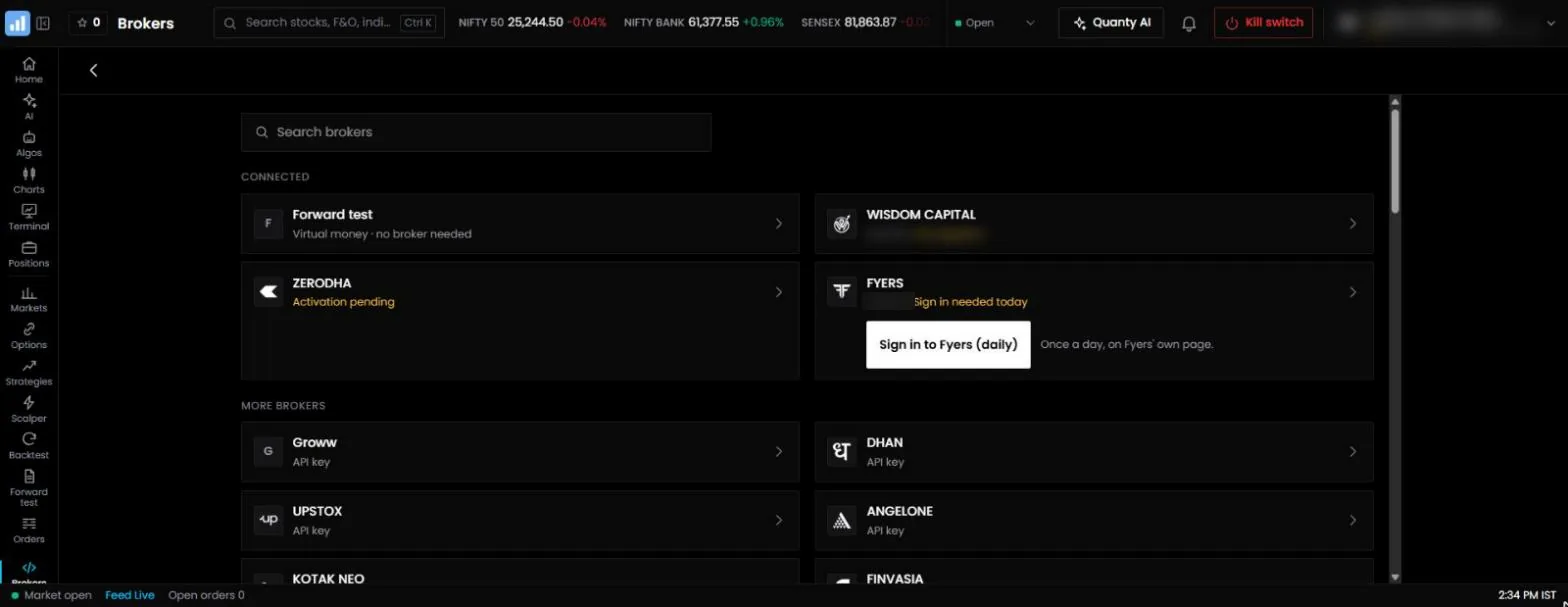
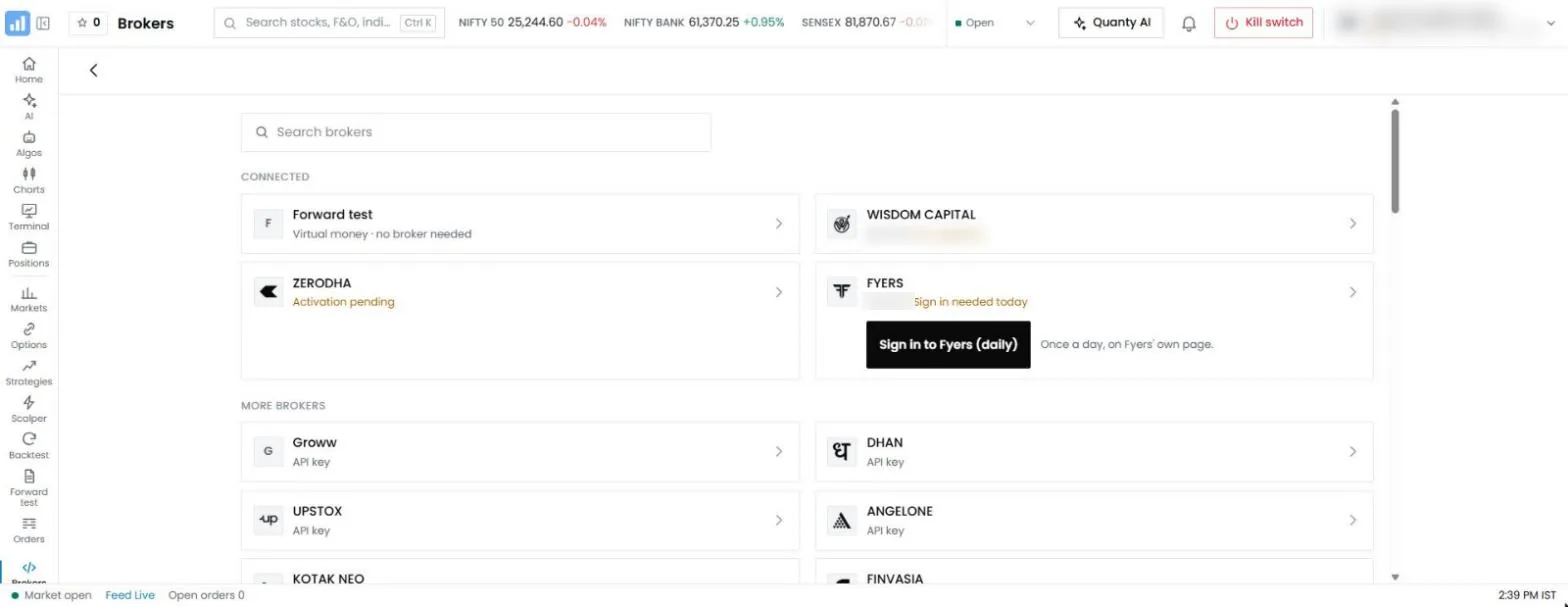
QuantPower connects to 100+ Indian brokers. For most, you enter your broker's API key once and it is stored encrypted; for Zerodha, Upstox and Fyers you sign in on the broker's own page and your password never reaches QuantPower. Live prices come through your connected broker. Without a connected broker the app shows no live prices, because exchange rules allow real-time data only through a data agreement or your broker. Some brokers charge for API access or market data, so check your broker's terms.
Where option analytics is going
Option analytics keep moving from the professional desk to the retail screen. Measures that only dealers watched a few years ago, such as gamma exposure and the volatility smile, now sit beside the chain. The next step is explanation: tools that say in plain words what a chain shows, without telling the trader what to do. In QuantPower, Quanty can explain an indicator or a Greek and build a strategy for you to check, but it is software, not an adviser, and it gives no calls. Rules keep changing too: lot sizes, expiry days and margins have all changed since 2024, so analytics that read today's contract details from the exchange's own files matter more than ever. QuantPower reads the list of F&O stocks from the exchange's instrument file each day, rather than keeping a fixed list, because the NSE changes that list every few months and a fixed list soon goes out of date.
Pricing
The option chain, the analytics, the strategy builder, charts and the screener are free in QuantPower. Tokens (1 token = ₹1, GST extra) pay for automation and AI: a live algo costs 200 tokens per 28 days, a Forward-test algo 100, a backtest 2 with the first 10 each week free, and a Quanty text question 1 with the first 5 each day free. See pricing.
Related guides
- Option chain: read a chain column by column
- Option greeks: delta, gamma, theta, vega and rho with Nifty examples
- Nifty PCR: what the put-call ratio and OI say
Start with 500 free tokens
Connect your broker, build a strategy and test it on paper before a single live order goes out.
Frequently asked questions
Does the QuantPower app show live option Greeks?
Yes. Delta, gamma, theta, vega and implied volatility are shown for every strike, live from your connected broker's prices.
What does the analytics screen show?
The put-call ratio, max pain, call and put walls, the at-the-money straddle and its IV, the zero-gamma level, and charts by strike for open interest, change in OI, the IV smile, the straddle premium and gamma exposure.
Can I place an order straight from the option chain?
Yes. Tap a strike's row, then Buy or Sell. The order sheet opens with the chain's quantity and the margin, and the order goes to your connected broker.
Which underlyings does the chain cover?
Nifty, Bank Nifty and Sensex options, and options on every stock in the F&O list. Stocks in the F&O ban are marked.
What is gamma exposure (GEX) on the chain?
An estimate, strike by strike, of how much the option sellers would have to buy or sell the underlying to stay hedged as it moves. The analytics screen also marks the zero-gamma level, the price at which that net gamma changes sign. It rests on an assumption about who holds which side, so read it as a rough map, not a forecast.
Is the option chain free?
Yes. The chain and the analytics cost no tokens. Live prices need your own connected broker account.
References
- Fischer Black and Myron Scholes, "The Pricing of Options and Corporate Liabilities", *Journal of Political Economy* 81(3), 1973
- Robert C. Merton, "Theory of Rational Option Pricing", *Bell Journal of Economics and Management Science* 4(1), 1973
- NSE: history of the equity derivatives segment, index options from 4 June 2001 (nseindia.com)
- SEBI, circular "Measures to strengthen Equity Index Derivatives framework for increased investor protection and market stability", 1 October 2024 (sebi.gov.in)
- NSE, circular on the revision of expiry days of derivatives contracts, effective 1 September 2025 (nseindia.com)
- NSE, revision in market lot of index derivative contracts from the January 2026 series (nseindia.com)
- QuantPower: option chain views, analytics and order path, from the app's code, checked 12 November 2026